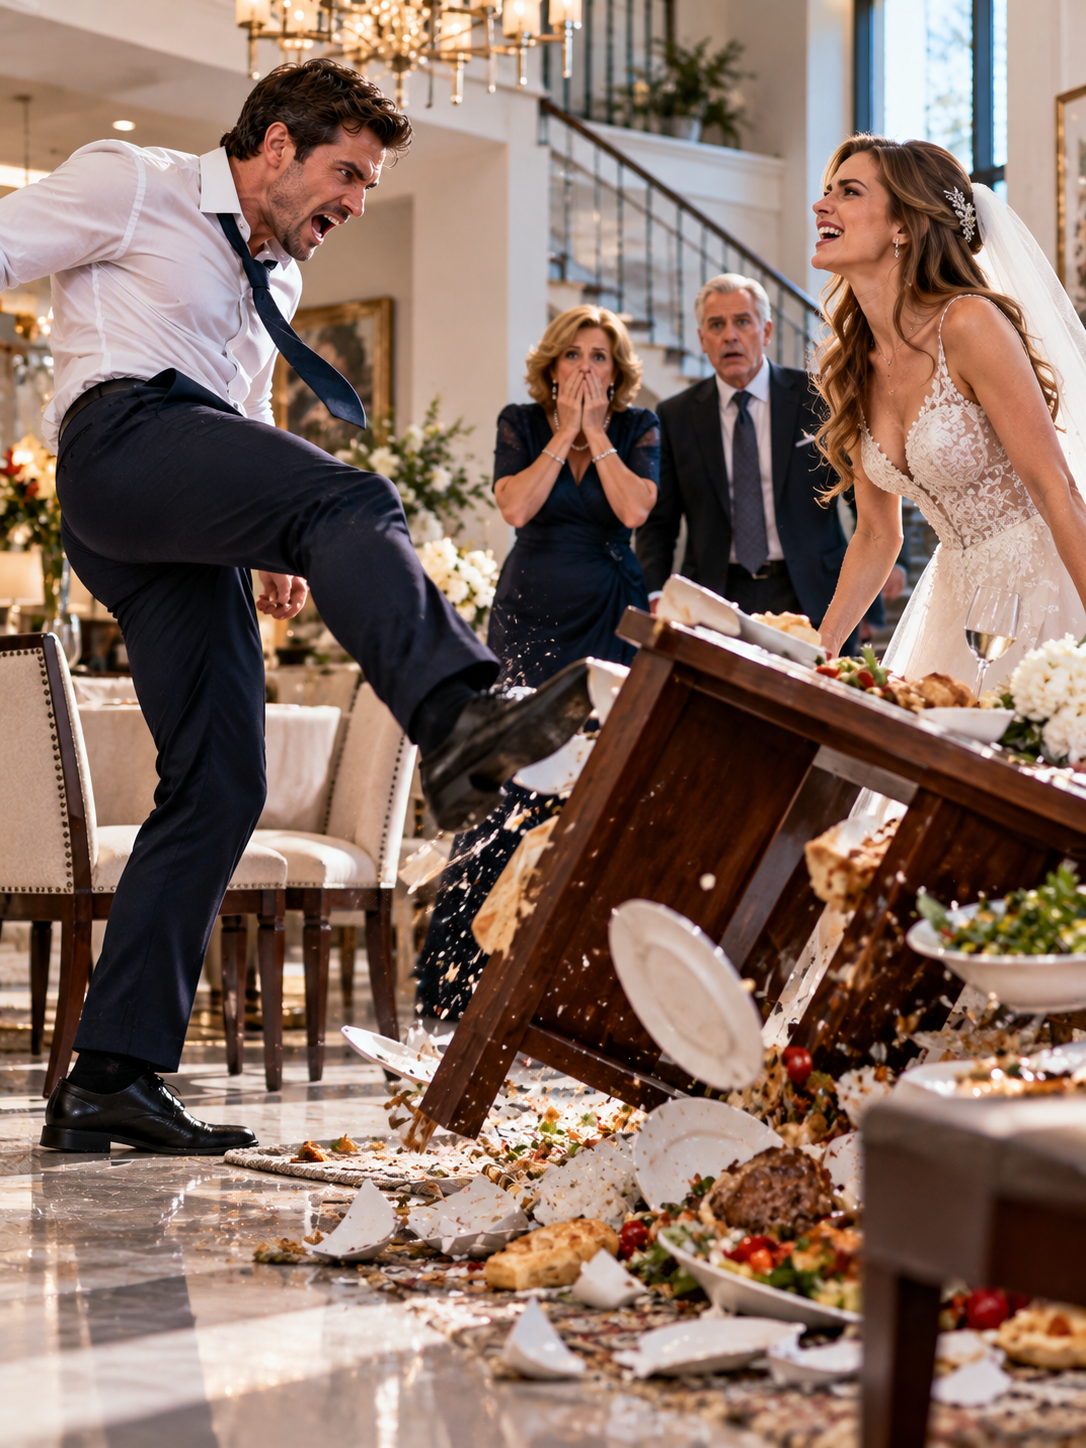
Three Days After Our Wedding, My Husband Kicked Over the Dinner Table and Threatened to Teach Me My Place—He Didn’t Know I Was About to Destroy His Plan
Three days after our wedding, my husband kicked our dinner table across the room because I served dinner late. Then he raised his hand and warned me that stubborn wives needed to be taught obedience. Instead of begging, I smiled and told him he had made a terrible mistake. He thought marrying me meant owning my home, my bank accounts, and my future. But when I discovered why he’d been so desperate to marry me, I realized his cruelty was only the beginning.
Part 1
The dining table hit the floor with a crack so loud that my neighbor began pounding on the wall. Roast beef slid across the hardwood, gravy splashed against my kitchen cabinets, and my favorite porcelain serving dish shattered beneath one of the overturned chairs. My husband stood in the middle of the wreckage, breathing heavily, with his polished leather shoe still raised from kicking the table. We’d been married exactly three days, and I was looking at a man I suddenly didn’t recognize.
“A wife who can’t even serve dinner on time needs to learn her place!” Derek Hollis shouted, pointing at the clock above my refrigerator. I’d arrived home fifty minutes late because a storm had flooded several streets in downtown Philadelphia, and I’d spent another hour preparing the meal he demanded. When I explained that traffic had been impossible, he stepped toward me and said, “Excuses are what lazy women make when they think their husbands are too weak to discipline them.” The expression on his face told me he wasn’t joking.
My name is Natalie Mercer, and I was thirty-seven when I married Derek after an eighteen-month relationship. I worked as a senior financial risk analyst, owned my condominium outright, and had spent most of my adult life building a life that didn’t depend on anyone else. Derek had seemed comfortable with my independence, often telling friends that my ambition was one of the reasons he loved me. Watching him advance across my ruined dining room, I understood how easily someone could imitate respect until he believed he no longer needed to.
“Starting tomorrow, you’re getting up at five to prepare breakfast,” he announced. “You’ll give me access to your checking accounts, your investments, and every credit card you have.” He grabbed my wrist when I tried to step around the broken dishes, then released it when I told him firmly to let go. “And when I tell you to do something, Natalie, I expect you to listen the first time.”
I felt fear rising beneath my ribs, but I refused to let it make my decisions. “You married a wife, Derek, not an employee,” I answered, moving toward the doorway. His expression darkened, and he raised his hand as though he intended to strike me. I stepped backward into the hallway, out of his reach, and told him that if he touched me, I would call the police.
He laughed and insisted I wouldn’t dare humiliate my husband over a domestic disagreement. I pointed toward the security camera above the entrance, which recorded silent video whenever movement was detected. Its green indicator was flashing, and Derek stared at it before lowering his arm. “You think a camera is going to make you the boss in this marriage?” he asked.
“No,” I replied. “I think the fact that this is my home means you don’t get to destroy it or threaten me.” I called the building’s security desk and requested assistance while keeping the hallway between us. Derek muttered that I would regret making a scene, then disappeared into the guest bedroom to collect the luggage we hadn’t unpacked from our honeymoon. By the time two security officers arrived, he’d transformed his anger into an offended silence.
He left carrying a suitcase and claiming he’d married an unstable woman who couldn’t handle ordinary marital expectations. I photographed the broken furniture, saved the camera footage, and contacted the police to document his threatening behavior. When the apartment finally became quiet, I sat on the kitchen floor and stared at the gravy drying beneath the refrigerator. I wasn’t crying over the table; I was thinking about how carefully Derek had chosen the moment to reveal himself.
Two weeks before our wedding, he’d encouraged me to apply for a larger house with him outside the city. He’d supplied pay statements, investment records, and what appeared to be a substantial portfolio managed by a private investment firm. I had accepted his explanations because his career as a regional logistics director seemed legitimate. Now I remembered how urgently he’d pushed me to combine our finances immediately after the ceremony.
I opened the financial documents he’d emailed me during our mortgage discussions. At first, everything looked ordinary, but the investment statement contained account numbers in a slightly different font from the surrounding text. Several transaction dates also seemed inconsistent with the activity described. I called my older brother, Simon, who worked in commercial lending compliance, and asked whether he’d help me examine information Derek had voluntarily shared during our mortgage application.
“What’s going on?” Simon asked, hearing something unusual in my voice. I told him about the dinner, Derek’s threats, and the suspicious statements, and he immediately urged me to secure the apartment and contact an attorney. Then he asked whether Derek had ever persuaded me to sign documents I hadn’t received copies of. I remembered the estate-planning packet Derek had brought home shortly before our wedding.
I told Simon that I’d signed what Derek described as routine medical authorization forms, which he’d taken away to have notarized. My brother went quiet before asking me to confirm the exact date. Twenty minutes later, he called back after locating a public property-record entry associated with my condominium. A mortgage had been recorded against my home four days before our wedding.
The borrower authorization carried my signature, but I had never applied for that loan.
Part 2
I spent the next morning in my attorney’s office, staring at a document that supposedly authorized a $420,000 mortgage against my condominium. Paige Dawson, a real estate and family law attorney Simon had recommended, examined the recorded paperwork beneath a desk lamp. My signature appeared on the final page, followed by a notary’s stamp dated four days before my wedding. The problem was simple: I hadn’t signed a mortgage, and I had never agreed to guarantee Derek’s debts.
“The recording doesn’t make an unauthorized mortgage valid,” Paige explained, “but we need to challenge it promptly before anyone tries to enforce it.” She asked me to describe every document I’d signed during our engagement, including anything Derek had presented as a routine household matter. I remembered sitting at his mother’s kitchen table, reviewing a medical authorization packet while his mother served coffee. Derek had collected the papers afterward, insisting his family’s attorney would handle the rest.
Simon arrived carrying copies of public business filings and civil court records. He’d discovered that Derek was associated with three equipment-leasing companies, none of which he’d disclosed during our mortgage application. Two had been sued by commercial lenders over unpaid obligations, and a third appeared in a collection action involving equipment that couldn’t be located. Together, the disclosed claims approached eight hundred thousand dollars.
I stared at the documents, remembering how Derek had criticized my reluctance to purchase a larger suburban house. He’d told me my financial caution proved I didn’t fully trust him, then apologized with flowers and a weekend trip. He’d also insisted that we marry before October, claiming his mother wanted to host a family celebration before winter. What I’d interpreted as romantic impatience now looked suspiciously like a deadline.
Paige contacted the lender identified in the recorded mortgage, Harbor Point Capital, and notified its legal department that I disputed the signature and authorization. She also arranged to preserve the relevant records and begin proceedings to challenge the mortgage against my property. I froze my credit files, changed my financial passwords, and instructed the building management not to admit Derek without my permission. The practical tasks gave me something useful to do while my understanding of the marriage collapsed.
That afternoon, Derek called from an unfamiliar number and sounded almost gentle. “Natalie, I know I lost my temper, but you embarrassed me in front of security,” he complained. I told him that his behavior had frightened me and that our attorneys would handle further communication. His voice immediately sharpened when I mentioned the mortgage.
“You’ve been going through my private business affairs?” he demanded. I reminded him that a mortgage against my home was very much my business. He said the paperwork was merely part of an investment arrangement intended to benefit us both. When I asked why he’d never mentioned a $420,000 obligation, he hung up.
His mother called less than an hour later. Vivian Hollis had always presented herself as the gracious owner of a historic estate outside Doylestown, with antique furniture, elaborate holiday dinners, and constant references to the family’s distinguished history. “Sweetheart, Derek is devastated,” she began, sounding as though she were consoling me after an unfortunate accident. “Marriage requires patience, especially when a man has serious responsibilities.”
I asked Vivian whether she knew about the mortgage Derek had recorded against my condominium. The warmth disappeared from her voice, replaced by the clipped authority she’d occasionally displayed toward restaurant servers. “Derek has financial commitments that you don’t understand,” she said. “You married into this family, Natalie, and family members are expected to help each other.” I told her that marriage hadn’t given Derek permission to forge my signature or threaten me.
“Be careful with accusations you can’t take back,” Vivian replied before ending the call. I sat motionless, hearing the refrigerator hum behind me, because she hadn’t sounded surprised by anything I’d said. That evening, Paige called with information from the lender’s preliminary response. Harbor Point had received the mortgage paperwork through a private broker who represented himself as authorized to coordinate financing for the Hollis family.
The broker’s application included a property valuation, photographs of my condominium, and details of my income. Some information could have come from our home-buying application, but other details had been collected much earlier. A photograph of my living room showed the Christmas decorations I’d removed in January. Derek hadn’t proposed until February.
For months before asking me to marry him, someone had been preparing to borrow against my home.
Part 3
On Thursday morning, Simon brought me copies of several documents obtained through lawful business-record searches. Derek’s financial disclosures listed an investment account worth nearly six hundred thousand dollars, but the investment firm’s contact information didn’t match its legitimate corporate records. The statement’s formatting also differed from authentic examples Paige had obtained for comparison. I remembered congratulating Derek on his responsible financial planning, and the memory made me feel foolish.
Paige reminded me that sophisticated deception could fool anyone who had no reason to expect it. She had requested records from Harbor Point, including the original authorization, the broker’s submission, and information about the notary. Meanwhile, my building manager confirmed that Vivian had visited my condominium in December, accompanied by a woman carrying a camera and measuring equipment. I’d believed they were gathering ideas for a family renovation project.
The realization unsettled me more than Derek’s angry phone calls. Vivian had complimented my walnut cabinets, admired the balcony view, and asked whether I still owed money on the property. I’d proudly told her that I had finished paying the mortgage three years earlier. She’d smiled and said, “A young woman with a paid-off home is a fortunate woman indeed.”
That afternoon, I returned to my office and asked my supervisor for several days of personal leave. She looked concerned when I explained that my new marriage had become a legal problem involving my property. Instead of pressing for details, she told me to take the time I needed and reminded me about our employee assistance program. I nearly cried because a woman I worked with treated my safety as more important than my husband had.
By Friday, Paige had obtained a copy of the estate-planning packet I originally signed. Derek had left an electronic version in our shared household folder, and its signature page matched the signature on the disputed mortgage almost perfectly, including a small accidental ink mark. A document examiner would need to evaluate the originals, but the resemblance strengthened our concerns. More importantly, the mortgage carried the name of a notary whose appointment status could not be verified for the stated date.
Paige arranged an urgent court conference regarding the disputed lien. Harbor Point’s counsel agreed that enforcement steps would remain on hold while the parties examined the authenticity of the documents, without admitting that the lender had done anything wrong. I understood that protecting my home would require more than one hearing and that no single conversation could erase a recorded mortgage. Still, knowing nobody could simply arrive and seize the condo that afternoon allowed me to breathe again.
That evening, Derek appeared at my building despite the instructions I’d given management. Security refused to admit him, and he called repeatedly from the lobby, insisting that our marriage was worth saving. When I finally answered through the intercom, he said, “Natalie, you don’t understand what happens if that loan falls apart.” I told him he should explain his concerns to Paige instead of appearing uninvited at my home.
He struck the intercom panel with his palm and shouted that I had no idea what his family stood to lose. The security supervisor intervened, and Derek eventually left after being told the police would be contacted if he refused. I saved the incident report and added it to the records I’d already gathered. What frightened me wasn’t simply his anger, but the desperation beneath it.
The following morning, Simon discovered that Vivian’s family estate had faced serious financial trouble before my engagement. Public filings showed overdue obligations, litigation over a commercial guarantee, and a threatened foreclosure that had been postponed. Then Paige received information showing that a substantial portion of the Harbor Point loan proceeds had been directed to an entity connected with the Hollis estate. Those funds appeared to have helped satisfy obligations that might otherwise have forced Vivian to sell.
I sat at the kitchen counter studying the transfer timeline. Derek hadn’t merely been hiding personal debt or hoping to share my savings after marriage. My unencumbered condominium had been used as security for money benefiting a family that had welcomed me with champagne and elaborate promises. Vivian had visited my home months before the proposal because she wanted to know what it was worth.
Then Paige forwarded a message from Harbor Point’s attorney. The lender had scheduled a meeting to review the disputed mortgage and the broker’s representations, and Derek had insisted on attending. Paige asked whether I wanted to participate with her.
I agreed, because I needed to hear what my husband would say when he could no longer pretend the documents were innocent mistakes.
Part 4
The conference room at Harbor Point Capital smelled of fresh coffee and expensive leather furniture. Derek sat across the table wearing a gray suit, looking tired but still determined to control the conversation. Vivian occupied the chair beside him, her pearls resting above a cream-colored blouse. Neither greeted me when Paige and I entered with our files.
The lender’s attorney, Malcolm Reed, began by explaining that Harbor Point had advanced money based on documents representing my consent. He emphasized that his client disputed any suggestion that it had knowingly accepted forged paperwork. Paige explained the signature discrepancies, questioned the notarial acknowledgment, and presented evidence that the source document had been a medical authorization. She also showed the lender’s representatives proof that I had never authorized the mortgage.
Derek leaned forward and insisted I’d understood everything before the wedding. “Natalie knew we were restructuring family investments,” he said, avoiding my eyes. Paige asked him to identify one conversation in which I’d agreed to pledge my condominium against his business debts. He mentioned general discussions about buying a house together, but couldn’t identify a signed mortgage authorization that he’d personally watched me execute. His certainty began to weaken as the questions became more specific.
Vivian finally interrupted, claiming the loan had saved jobs and prevented a family financial disaster. I asked how that justified using my home without permission. “Because you married into a family with obligations,” she answered sharply. “You have a perfectly good career, substantial savings, and a beautiful apartment, while Derek has people depending on him.” I looked at her and realized she considered my financial independence an inconvenience to be overcome.
Malcolm then introduced correspondence obtained from the financing broker. Several emails showed Derek and Vivian discussing my property’s value long before our engagement, including one in which Vivian described me as an ideal financial partner. Another message mentioned that Derek expected me to agree to family financing once we were married. Paige requested copies for the legal proceedings, and Malcolm agreed to preserve them pending formal disclosure.
I turned toward Derek and asked him when he’d decided that marrying me was the easiest way to rescue his family’s finances. He stared at his folded hands before saying, “I did love you, Natalie, and I still do.” I reminded him that he’d threatened me over a late dinner only three days after our wedding. Love, I told him, didn’t explain a forged mortgage or a plan to take control of my bank accounts.
When the meeting ended, Harbor Point maintained its agreement to suspend enforcement while the authentication dispute proceeded. Its representatives also confirmed that the lender would cooperate with the formal document-review process. Vivian left first, complaining that everyone was treating an ordinary business disagreement like a crime. Derek remained standing near the conference table, looking at me with resentment that hadn’t disappeared.
“You’ve ruined my career,” he said when the others moved toward the door. I told him his business decisions had created the problem long before I discovered them. He stepped closer, but a security employee moved into the doorway before he reached me. I left with Paige, my legs trembling once we reached the elevator.
Over the following weeks, the legal process revealed additional irregularities in the financing documents. The notarial acknowledgment could not be substantiated, and Derek’s explanations repeatedly conflicted with the preserved records. The lender eventually agreed to release its claim against my condominium as part of a negotiated resolution, while retaining whatever lawful claims it might have against the actual borrowers. Paige continued the necessary court proceedings to ensure the invalid mortgage was removed from my property’s title.
Meanwhile, Derek’s employer began reviewing concerns about his outside business activities. I learned through my attorney that he had been placed on administrative leave after questions arose about representations made to several commercial lenders. Vivian’s estate was still facing financial pressure, and she began sending me messages asking for a private settlement. I declined every invitation and instructed her to communicate through counsel.
One Friday afternoon, Paige called with confirmation that the mortgage release documents had been executed. I stood beside my balcony doors, listening as she explained the remaining filing steps and the timeline for obtaining a clean title record. My home was finally moving out of the shadow of Derek’s financing scheme. Then Paige told me that Derek had requested a private meeting before the marriage case proceeded.
According to his attorney, Derek wanted to apologize, explain the full circumstances, and ask whether I would consider remaining married. I looked at the ruined dining table, which I’d kept in storage as evidence, and remembered the way he’d raised his hand toward me. He’d wanted my obedience when he believed I had no choice.
Now that he was losing everything he’d tried to obtain, he suddenly wanted my forgiveness.
Part 5
I agreed to hear Derek’s explanation, but only in Paige’s office with our attorneys present. He arrived wearing an inexpensive jacket instead of the tailored suits he used to favor, and there were dark circles beneath his eyes. For several minutes, he talked about his company’s financial problems, his mother’s struggling estate, and the pressure he’d felt to rescue his family. He sounded almost reasonable until he described my financial security as an opportunity he’d been foolish not to use.
“Did you know about the mortgage before you proposed?” I interrupted. Derek stared at the carpet, then admitted he’d discussed using my home as collateral with his mother months before our wedding. He insisted that he’d planned to explain everything eventually and believed I would have agreed if he’d presented the arrangement properly. I asked why he’d needed to falsify documents if he truly believed I’d consent.
He had no answer beyond saying that everything had become more complicated than he expected. Then he reached across the desk and told me he still wanted a future together. “We can start over, Natalie,” he said. “I’ll get another job, we’ll work out the finances, and nobody has to know what happened.” I looked at him and realized he was still asking me to help protect his reputation.
“Derek, you threatened to hit me because dinner was late,” I reminded him. “You tried to take control of my accounts, and you used documents I signed for another purpose to obtain money against my home.” His face tightened as I continued, explaining that I wasn’t interested in pretending those decisions were ordinary marital difficulties. When he asked whether I could ever forgive him, I told him forgiveness was not something he could negotiate.
Our attorneys handled the remaining discussions, and I left without looking back. Over the following months, the lender’s release was recorded, and Paige confirmed that the disputed mortgage no longer burdened my condominium’s title. My personal accounts remained separate, and the financial records established that I had not authorized Derek’s commercial obligations. The related document irregularities were referred to the appropriate authorities, although I understood that any investigation would proceed independently of my marriage case.
Derek and I ultimately divorced after the necessary legal proceedings. Because our marriage had been so brief and the condominium was property I owned before it, the financial separation was considerably simpler than Derek had once suggested. Paige obtained a final order resolving our marital claims, and I kept the home I’d purchased through years of work. Derek’s remaining commercial debts were his problem to address, not mine.
Vivian contacted me several times afterward, alternating between accusations and emotional appeals. In one message, she claimed Derek had ruined his life because I’d refused to cooperate with a reasonable family arrangement. In another, she said he had loved me more than any woman he’d ever known. I blocked her number after explaining once that I would not discuss financial assistance or reconciliation.
The most surprising part of rebuilding my life was how ordinary it became. I replaced the broken dining table with a smaller oak one, repainted the kitchen, and began inviting friends over for dinner again. Sometimes I still startled when something fell unexpectedly, and I sought counseling to work through the fear the confrontation had left behind. Recovery wasn’t as simple as changing the locks, but gradually my apartment began feeling like home again.
Simon visited one Saturday with groceries and offered to cook while I finished some work. He burned the garlic bread, spilled tomato sauce on the counter, and apologized so dramatically that we both started laughing. I realized I hadn’t laughed that freely in months. Later, we ate dinner at the new table, and nobody complained about whether the meal had arrived on schedule.
A few weeks after the divorce became final, Derek sent a letter through his attorney. He wrote that he’d started counseling, accepted responsibility for his behavior, and regretted allowing his mother’s expectations to influence his decisions. He also asked whether we could meet one more time, without lawyers, just to remember the happier parts of our relationship. I read the letter once and placed it in the folder containing the final divorce documents.
I didn’t respond because I no longer needed another explanation. Derek had known what he was doing when he accepted money secured by my property and when he tried to frighten me into giving him financial control. His regret had arrived only after the scheme collapsed and the woman he’d underestimated refused to rescue him. Whatever lessons he learned afterward belonged to his future, not mine.
Nearly a year after the wedding, I stood in my kitchen preparing dinner on a rainy Tuesday evening. The windows were fogged from the heat of the oven, and the smell of rosemary filled the apartment. I checked the clock and realized the roast would be ready almost an hour later than I’d planned. For an instant, I remembered Derek’s furious face and the sound of porcelain breaking against the floor.
Then I poured myself a glass of water, turned on some music, and went back to chopping vegetables. No one was waiting to punish me, threaten me, or demand access to money I’d earned before they entered my life. I could eat dinner at six, seven, or midnight, and the choice belonged entirely to me.
I’d once thought the worst mistake of my life was marrying Derek Hollis. Eventually, I understood that trusting someone wasn’t the mistake; ignoring the truth after they revealed themselves would have been. He believed a marriage certificate gave him authority over my life, and for three days he behaved as though my independence had finally come to an end.
What he never understood was that I hadn’t spent years building my career, my home, and my confidence just to surrender them to a man who mistook cruelty for strength.
He wanted to teach me my place.
I taught him that my place was wherever I chose to stand, and that he would never be standing beside me again.
Legal Notice: This story is a work of fiction. Names, characters, businesses, events, and incidents are the product of the author’s imagination or are used fictitiously. Any resemblance to actual persons—living or dead—or to actual events is purely coincidental. Thank you! 💓