I Spent $680,000 Saving My Parents’ House. At 1 A.M., They Banned Me From Thanksgiving—Then My Sister’s Perfect Dinner Fell Apart
At 1:04 in the morning, my mother sent me a message that ended thirty-eight years of pretending my family loved me equally. I had spent $680,000 saving my parents’ house from foreclosure, but my younger sister decided I wasn’t sophisticated enough to attend Thanksgiving dinner. My mother expected me to accept the humiliation quietly, as always. I replied with one word: “Noted.” What they didn’t know was that a contract they’d signed six months earlier was about to change everything—and my sister had been hiding something even worse.
Part 1
My phone vibrated against the wooden nightstand, waking me from the first decent sleep I’d had in days. Outside my Seattle apartment, November rain rattled the windows, and the digital clock read 1:04 a.m. I expected another emergency from work, because being a senior cloud infrastructure architect meant someone always needed me when a system failed. Instead, the screen displayed a message from my mother, Judith Vale, that made me sit upright before I’d even finished reading it.
“We know you spent $680,000 saving our house, Catherine, but Sloane doesn’t want you at Thanksgiving.” A second message followed immediately: “She’s hosting important business guests, and she thinks your presence might make things uncomfortable. Please understand that we’re trying to support your sister’s future.” I stared at the glowing screen while my bedroom heater clicked on, searching for any sign that my mother understood what she’d just said. There wasn’t one.
My sister, Sloane, was twenty-nine, beautiful, charming, and extraordinarily skilled at turning other people’s money into evidence of her own success. She called herself a lifestyle strategist, although her previous businesses included an online boutique that lasted four months and a wellness subscription service that disappeared after her suppliers demanded payment. Every failure became somebody else’s fault, and every rescue became proof that her next venture would succeed. Meanwhile, I was the boring older daughter who worked late, drove an aging Subaru, and somehow always had the money to fix emergencies.
Six months earlier, my father had called while I was reviewing a security migration at work. His architecture consulting business had collapsed under commercial loans, and the bank was preparing to foreclose on our childhood home in Magnolia. The total needed to clear the immediate crisis, including outstanding debt, penalties, and property taxes, was $680,000. When I arrived that evening, my mother was crying beside a stack of unopened envelopes while Dad sat at the kitchen table, unable to meet my eyes.
I sold my Tacoma rental duplex, liquidated nearly every investment account I owned, and transferred the money through a closing attorney. It wasn’t spare cash, and it wasn’t money I’d inherited; it represented fifteen years of overtime, postponed vacations, and careful financial decisions. Dad had hugged me in the bank parking lot and promised, “Catherine, we’ll repay every dollar before Thanksgiving.” Mom had called me their miracle, while Sloane sent a heart emoji from a resort in Mexico.
Now, seventy-two hours before Thanksgiving, my mother was telling me I wasn’t welcome at the table my money had saved. I thought about calling her, but I already knew how the conversation would go: Sloane was sensitive, Dad was stressed, and I was mature enough to understand. My feelings would become a problem requiring an apology from me. Instead, I typed a single word, “Noted,” and pressed send.
For several minutes, I sat listening to the rain and remembering all the holidays when I’d been expected to accommodate Sloane. At twenty-three, I’d paid her overdue apartment deposit; at twenty-seven, I’d covered the insurance deductible after she damaged Dad’s car; and last Christmas, I’d quietly paid for the catering she claimed to have organized. I wasn’t keeping score then, because I’d believed families helped each other. But lying awake with that message on my phone, I finally understood the difference between helping someone and financing their disrespect.
I walked into my home office and opened a folder labeled Magnolia Property—May Agreement. Inside were the promissory note, the recorded deed of trust, and the repayment schedule my attorney, Sylvia Keene, had insisted we prepare. My parents had signed every page knowing the $680,000 was a secured loan, not a gift, and that failure to repay would allow me to pursue the property through lawful enforcement. The final repayment date was Thanksgiving Day.
I remembered Sylvia’s warning when we’d signed the agreement in May: “Catherine, don’t let love substitute for legal protection, especially when everyone is frightened and promising things they haven’t planned how to deliver.” Dad had assured her that refinancing was practically approved, and Mom had squeezed my hand, insisting I would never need those documents. I had wanted to believe them badly enough that I ignored the tightness in my stomach. Tonight, for the first time, I was grateful Sylvia hadn’t.
I emailed Sylvia asking her to review the repayment status and prepare the appropriate notice if the deadline passed without payment. Then I searched my messages for the refinancing updates Dad had been promising since August. One forwarded email caught my attention because it contained an attachment I hadn’t opened, a financing summary addressed to a lender I’d never heard him mention. My father’s explanation had always been that approval was taking longer than expected, but the document showed something very different.
The lender had rejected his application almost three months earlier, and the correspondence revealed that Dad had been discussing another financial arrangement involving our family home. My stomach tightened as I read a line identifying Sloane as the proposed beneficiary of a new business funding package. I opened the next attachment, expecting to see a straightforward refinancing plan. Instead, I found a preliminary proposal that treated the money I’d lent my parents as though it had been an unconditional gift.
Part 2
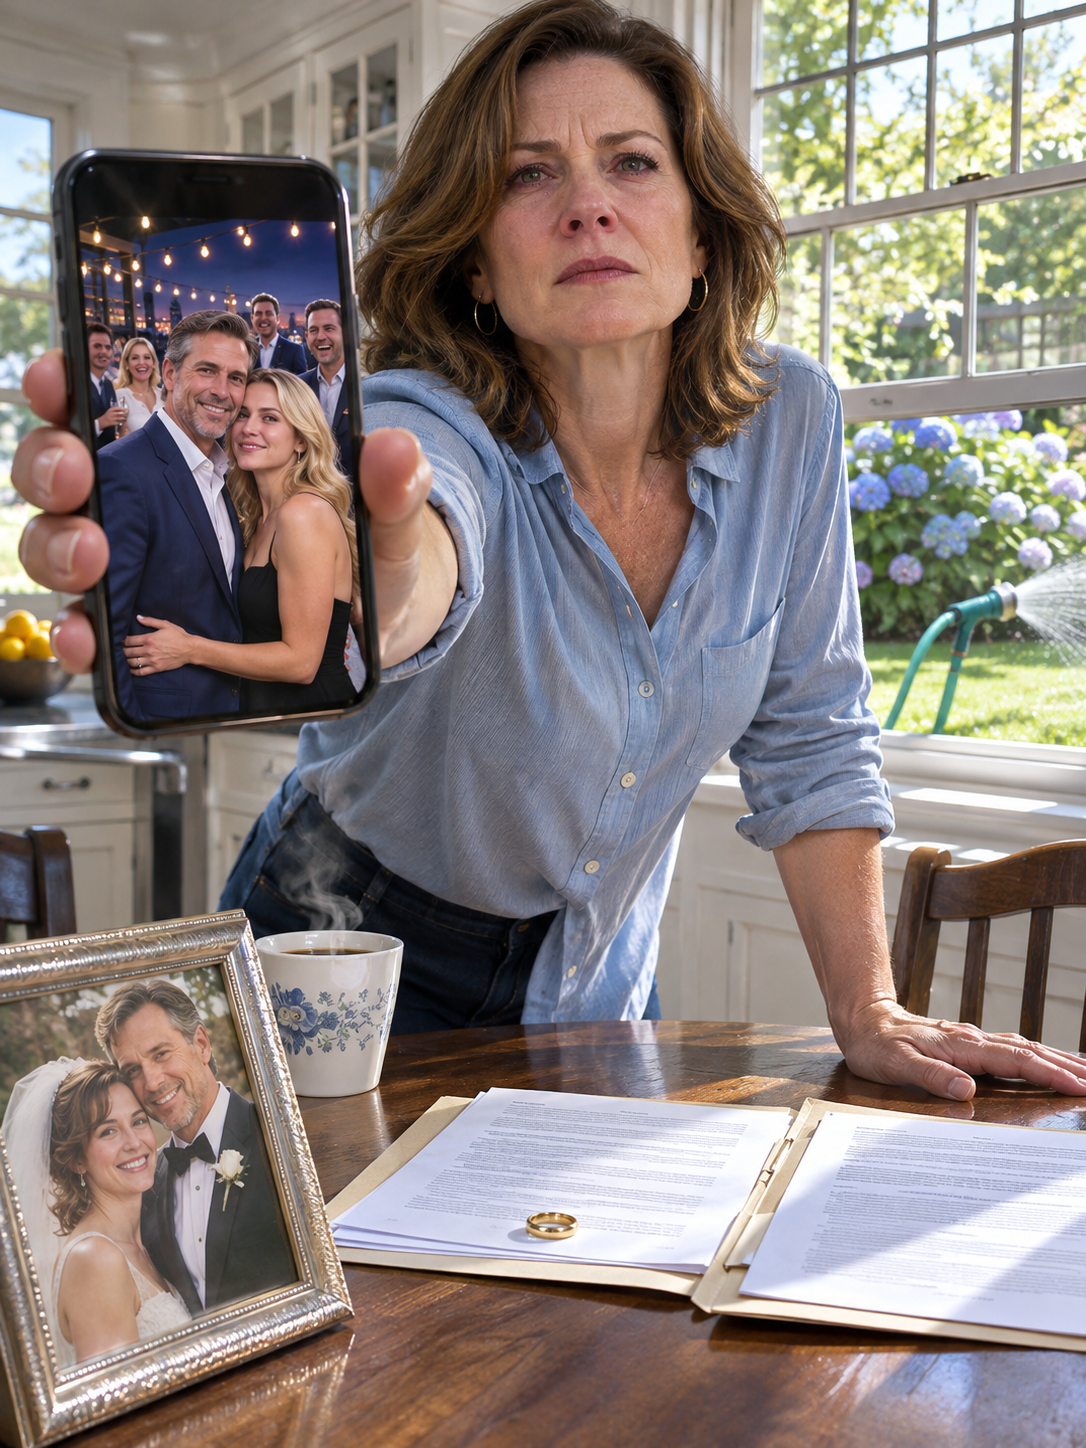
I reread the word “gift” until the letters began to blur. The financing summary described my $680,000 contribution as a voluntary family transfer that required no repayment, while the proposed business arrangement reserved future proceeds for Sloane’s consulting venture. Nothing in the document mentioned my recorded deed of trust or the agreement my parents had signed at Sylvia’s office. I checked the date and realized Dad had approved the preliminary summary four months after promising me my money was protected.
At 7:30 the next morning, I called Sylvia before making coffee. She listened while I explained the documents, then asked me to forward the complete email chain rather than isolated screenshots. “A lender’s proposal can’t simply erase your recorded security interest,” she said, “but misrepresenting the existing debt could create serious problems for everybody involved.” When I asked whether my father had committed fraud, she told me not to jump to conclusions before we understood what had actually been submitted.
I spent the morning at my office overlooking Elliott Bay, reviewing cloud access permissions while pretending I wasn’t waiting for Sylvia’s call. At noon, my coworker Denise appeared beside my desk carrying two paper cups and asked why I’d declined the company Thanksgiving gathering. I told her my family had changed its plans and handed me an invitation to stay home instead. Denise considered that for a moment, then said, “You can have dinner with my family, but you are not spending Thursday believing you weren’t worth a place at somebody’s table.”
Her kindness nearly made me cry, which irritated me more than my mother’s text had. I thanked her but explained that I’d already been considering a short trip to Maui, something I’d postponed for years because my family constantly needed financial help. After Denise left, I opened an airline website and booked a Thursday morning flight with a small cottage reservation in Kula. For once, I wasn’t asking whether anyone else approved of how I spent my time or money.
By midafternoon, the family group chat began filling with photographs of elaborate table decorations. Sloane had chosen white flowers, hand-lettered place cards, expensive candles, and a menu featuring ingredients our parents rarely bought for themselves. Her messages repeatedly mentioned Graham and Nora Ellis, a wealthy couple considering financing her new boutique consulting agency. Then Mom posted, “Everything is ready, sweetheart, and with Catherine not coming, we’ll have room for the presentation materials.”
I read that sentence twice before closing the app. My mother hadn’t merely accepted Sloane’s decision; she was celebrating the extra space created by my absence. A minute later, Dad sent a private message asking whether I could review an architectural software subscription he needed help renewing. There was no mention of Thanksgiving, the repayment deadline, or the fact that his youngest daughter had apparently removed his oldest from the family.
I called him because I wanted to hear what he would say when confronted directly. “Dad, have you secured the financing to repay my loan?” I asked, and the background television went quiet as he lowered the volume. He said the commercial market was difficult, lenders were cautious, and he had several promising projects coming soon. When I mentioned the August rejection letter, he paused so long that I could hear my mother asking what was wrong from across the room.
“Those documents are complicated, Catherine,” Dad finally said, sounding irritated. “You work with computers, not real estate financing, and I don’t want you misunderstanding something important.” I reminded him that I understood the six-figure loan agreement he’d signed and the money that had left my accounts. His answer was familiar: “Your sister has an opportunity to build something extraordinary, and this family needs to pull together.” He ended the call by asking me not to make Thanksgiving difficult.
Sylvia called that evening with news that made me put down the glass I was washing. My security interest was properly recorded, and Dad’s lender had already raised questions about the conflicting representations in the financing summary. More troubling, an investment presentation prepared for Graham Ellis described the Magnolia house as a debt-free family asset available to support Sloane’s business. Sylvia recommended that we preserve the documents, contact the lender through appropriate channels, and avoid making any accusations until we had confirmed their origin.
“Does Sloane know about my loan?” I asked, remembering how confidently she’d been planning her expensive dinner. Sylvia couldn’t answer, but she pointed out that the presentation contained financial details ordinarily obtained from someone with access to the family’s records. I remembered Sloane borrowing Dad’s laptop during a family dinner in September and dismissing my questions about what she was working on. Suddenly, that ordinary moment felt much less ordinary.
I opened Sloane’s public business website, where she’d already posted a photograph of the Magnolia dining room beside a description of her firm’s impressive financial foundation. Beneath it was a statement announcing that a substantial private family contribution had secured the company’s launch. The number wasn’t displayed, but the attached investor summary Sylvia had obtained included it. My sister wasn’t simply excluding me from Thanksgiving; she appeared to be using my $680,000 sacrifice as proof of her own financial credibility.
Part 3
Thanksgiving morning arrived cold and unexpectedly clear, with pale sunlight spreading across the Seattle skyline. I boarded my flight to Maui carrying one suitcase, two books, and a phone full of messages I no longer wanted to answer. Mom had written, “Hope you’re not upset, sweetheart. We’ll celebrate together another time,” while Dad asked whether I could transfer money for an overdue household expense. I ignored both messages and watched Mount Rainier disappear beneath the clouds.
Before departing, I had spoken with Sylvia about what would happen if noon passed without repayment. She explained that we could begin formal enforcement of my secured loan, although recovering the money through the property would require proper notice and legal procedures. A process server was scheduled to deliver the notice of default that afternoon, making it impossible for my parents to pretend the deadline hadn’t arrived. I asked Sylvia to proceed professionally and document everything, but I didn’t tell her to embarrass anyone.
During the flight, I connected to the onboard Wi-Fi and discovered that Sloane was broadcasting Thanksgiving preparations on social media. The dining table looked magnificent beneath the tall windows, decorated with white roses, crystal glasses, and polished silverware that had belonged to our grandmother. Five place cards stood beside the plates: Martin, Judith, Sloane, Graham, and Nora. My absence had become part of the decorations, carefully arranged to make everything appear more elegant.
Sloane posted a photograph of herself beside Graham Ellis, a silver-haired investment executive wearing an expensive charcoal sweater. Her caption described the gathering as “an intimate celebration of visionary partnerships and generational success.” Behind them, Dad stood near the fireplace with a smile I recognized from every family crisis he’d ever tried to conceal. His shoulders were rigid, and the hand holding his glass looked strangely tense.
At 12:17 p.m. Seattle time, Sylvia confirmed that the repayment deadline had passed without any money arriving in the designated account. She had also received written acknowledgment from the prospective lender that my security interest remained recorded against the house. “The notice will be served this afternoon,” she wrote, followed by a reminder that we still had time to negotiate a voluntary resolution. I thanked her and closed my tablet, suddenly feeling more exhausted than angry.
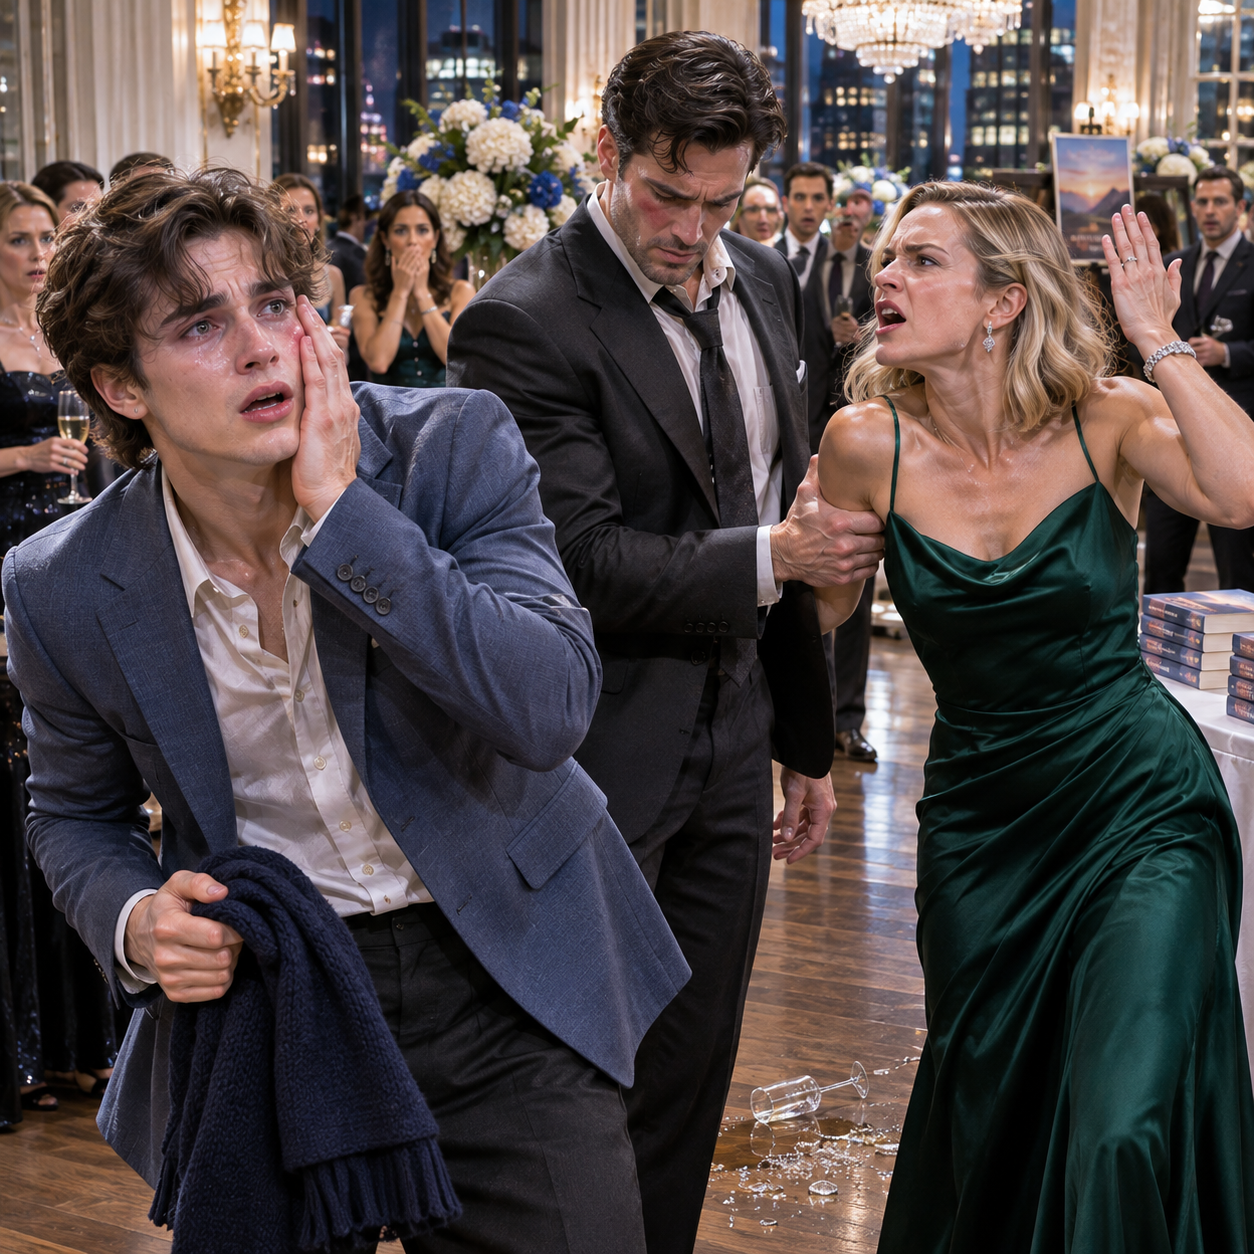
At 2:21 p.m., Sylvia sent another update: the process server had delivered the documents to my father at the house. According to his service report, Dad answered the door wearing his Thanksgiving clothes, and Mom initially tried to send the visitor away. When the server explained that the papers concerned the unpaid $680,000 loan secured against their property, Dad accepted the envelope without argument. Sloane, hearing the commotion, came into the hallway and demanded to know why someone was interrupting her guests.
I didn’t witness the confrontation, but the frantic messages arriving afterward painted an increasingly clear picture. Mom called eleven times, Dad sent three requests for me to contact him, and Sloane filled the family chat with furious accusations. “YOU SENT LEGAL PAPERS TO OUR HOUSE ON THANKSGIVING!” she wrote, followed by, “GRAHAM AND NORA SAW EVERYTHING!” Then came the message that told me the real damage had begun: “THEY’RE ASKING QUESTIONS ABOUT THE HOUSE!”
An hour later, Graham Ellis contacted Sylvia after obtaining her information from the notice. He explained that his investment review had relied on a presentation describing the Magnolia property as unencumbered and available to support Sloane’s proposed business. Learning about my recorded loan had raised immediate concerns about the accuracy of that presentation. He asked whether Sylvia could verify a document in his possession that supposedly confirmed my financial participation.
Sylvia forwarded the document to me through a secure email, asking that I examine it carefully before responding. It was a two-page statement describing a $680,000 contribution to Sloane’s business development, accompanied by an acknowledgment that I would not seek repayment. I recognized the amount, the date of my original transfer, and several phrases that resembled language from my family’s financial discussions. But the statement had nothing to do with the loan agreement I’d signed.
At the bottom of the second page was a signature above my printed name, Catherine Vale. The handwriting looked familiar because it had been copied from something I’d actually signed, but the spacing and faint gray border suggested a digital insertion. I enlarged the image and recognized the exact curve of my final letter from the agreement I’d executed six months earlier. Someone had taken my signature from a legitimate document and placed it on a declaration I’d never seen.
Part 4
I called Sylvia immediately, my hands trembling so badly that I nearly dropped the phone. “That’s not my signature on that agreement,” I told her, explaining where I believed the image had originated. She asked me to preserve the original email and refrain from contacting Sloane until the document could be examined properly. What had started as an insulting Thanksgiving exclusion had now become a possible falsification of financial records, and I realized the family drama was only part of the problem.
Graham suspended his investment discussions pending independent verification, and Sylvia informed his attorney that I disputed the document’s authenticity. By early evening, Sloane was calling from three different numbers and demanding that I tell Graham everything was a misunderstanding. When I finally answered, she shouted, “You’re destroying the biggest opportunity I’ve ever had!” I asked whether she’d used my signature without permission, and the silence that followed was more revealing than her previous twenty messages.
“I needed to show investors that our family had serious resources,” she finally admitted, speaking much more quietly. “Dad gave me copies of the property documents, and I thought you wouldn’t mind helping us get started.” I told her that borrowing a document wasn’t the same as obtaining permission to claim I’d invested my savings in her business. She replied that I’d always supported the family, so assuming I’d support her company wasn’t unreasonable. I ended the call because she still seemed incapable of understanding that my money belonged to me.
My mother called twenty minutes later, crying that the dinner had been ruined and Graham and Nora had left before dessert. She demanded that I call the investors, withdraw my complaint, and stop treating Sloane like a criminal. When I asked whether she knew about the financial statement, she admitted she’d seen it but believed Sloane was merely presenting our family favorably. “You’re her older sister,” Mom said, as though those four words erased every boundary I’d ever tried to establish.
I reminded her that she had uninvited me from Thanksgiving after I’d saved her home, and her voice hardened immediately. “You’re punishing us because your feelings got hurt,” she accused, adding that a good daughter wouldn’t bring lawyers into a family disagreement. I looked around my quiet cottage, smelling the rain-soaked eucalyptus outside the open window, and realized I had no desire to defend myself again. “Mom, you can discuss the financial agreement with Sylvia,” I said before hanging up.
On Friday, Dad called alone from his parked car and sounded older than I remembered. He admitted that refinancing had failed in August and that he’d hidden the rejection because he was ashamed. Sloane had convinced him that Graham’s investment could eventually solve their financial problems, but her business had no confirmed funding. “I kept thinking one more month would fix everything,” he said, and I answered, “You had six months, Dad, and you chose to lie through all of them.”
He asked whether I intended to take the house, and I explained that my goal was recovering my money, not putting them on the street. Sylvia could help arrange a voluntary sale, repayment agreement, or another lawful resolution, but I would not provide more funds or accept imaginary refinancing promises. Dad began crying and asked how I could be so detached after everything he’d done raising me. “I learned from you,” I replied, “that a quiet person can endure almost anything until she finally decides she won’t.”
The following week, Sylvia received confirmation that Graham had ended negotiations with Sloane’s company. The altered financial statement had destroyed his confidence in the information she provided, and he declined to continue discussions. Sloane blamed me publicly through vague social media posts about family betrayal, but I refused to respond. Sylvia was already preserving the relevant records and communicating with the appropriate parties, which mattered far more than winning an argument online.
My parents initially resisted selling, insisting that the house had been in our family for decades and deserved another chance. Sylvia sent them an accounting of the debt and explained the consequences of continued default, including the possibility of a foreclosure process if no agreement could be reached. Dad finally accepted a meeting with a real estate broker, while Mom complained that I was forcing them to surrender their retirement. I didn’t remind her that I’d surrendered my own investments to protect that retirement six months earlier.
Then Sylvia discovered something while reviewing the documents Dad had provided for the sale. In September, an independent buyer had offered $1.92 million for the Magnolia property, enough to repay me and leave my parents with substantial equity. Dad had declined the offer after Sloane insisted that selling the house would damage the image she was building for her investors. I stared at that rejected offer, realizing my parents hadn’t simply failed to repay me; they had chosen my sister’s appearance of wealth over an opportunity to make me whole.
Part 5
When I confronted Dad about the September offer, he didn’t deny it. He said Sloane believed Graham would be more impressed if our family maintained the Magnolia property, and Mom had agreed that selling before Thanksgiving would send the wrong message. I reminded him that the money represented my entire savings, not an inheritance or a gift I’d offered casually. Dad whispered, “I thought you’d understand,” and I answered, “I understand perfectly. You were willing to risk my future to protect hers.”
Six weeks later, after negotiations handled through our attorneys, my parents agreed to a voluntary sale of the property. The final purchase price was $1.86 million, slightly below the earlier offer but sufficient to repay my secured loan and cover the agreed transaction expenses. Sylvia arranged for the repayment to be made through closing, while the remaining equity went to my parents as the legal owners of the property. I received the full $680,000 I was owed, but recovering the money didn’t repair the relationship that had made the loan necessary.
Mom called after closing, sounding strangely cheerful for someone who’d spent weeks accusing me of ruining her life. She said they were considering a smaller condominium near Edmonds and wondered whether I might help Sloane restart her business once everything settled down. I listened while she described how difficult the previous month had been for my sister. Then I told her I would never finance Sloane again, and I wasn’t interested in another conversation about what my younger sister deserved.
“You’re really going to abandon your own family over money?” Mom demanded, her old anger returning instantly. I looked at the bank confirmation on my laptop and remembered the night she’d told me I wasn’t welcome for Thanksgiving. “No, Mom,” I said. “I’m refusing to let this family abandon me whenever it needs something and remember me whenever a bill arrives.” She cried that I had become cold and selfish, but I ended the call without apologizing.
Dad requested one final meeting before they moved out of Magnolia, and I agreed to meet him at a quiet café near the waterfront. He arrived wearing his old tweed coat, carrying a small wooden box of photographs he’d found while packing. Over coffee, he admitted that protecting Sloane from disappointment had gradually become more important than protecting me from exploitation. “You were always so capable, Catherine,” he said, looking down at his trembling hands, “and I mistook that for permission to ask you to carry everything.”
I believed his regret was genuine, but I also understood that sincerity didn’t reverse fifteen years of being taken for granted. He asked whether we could rebuild our relationship, promising that he would never request another dollar. I told him I hoped he would make better choices, but I wasn’t ready to pretend everything was forgiven because he finally understood the damage. When he reached across the table, I gently withdrew my hand and said, “I need a life where loving people doesn’t mean sacrificing myself.”
Sloane made one final attempt to contact me through an unfamiliar number, sending a message that mixed accusations with a request for financial assistance. She said Graham had refused further communication, several potential clients had withdrawn, and she couldn’t afford her apartment without help from our parents. Then she wrote, “You have everything, Catherine, and I have nothing. Doesn’t that make you feel guilty?” I read the message once, blocked the number, and returned to packing for my own move.
I had decided to leave my Seattle apartment and spend several months working remotely from a rented house overlooking the Oregon coast. For years, I’d organized my life around being close enough to rescue my parents whenever they called. Now I wanted mornings without emergency messages, weekends without guilt, and the freedom to spend money on experiences I’d always postponed. I bought a comfortable new car, arranged a vacation I’d dreamed about for years, and stopped explaining those decisions to anyone.
On my final evening in Seattle, I opened an old family photograph taken when Sloane was seven and I was sixteen. Dad stood beside me while I held an academic award, but his attention was fixed on Sloane, who was crying because she hadn’t received a present. I remembered that afternoon vividly, especially how quickly my accomplishment had disappeared beneath the urgency of comforting her. For the first time, I looked at the picture without wishing I could somehow become important enough to deserve the same attention.
I packed the photograph into a storage box and closed the lid. My parents had received the proceeds remaining from their home sale, and whatever they chose to do with that money was now their responsibility. If they spent it wisely, they could live comfortably; if they used it to rescue Sloane again, I would not be the person who rescued them afterward. My relationship with them was no longer an emergency waiting for me to solve it.
The next morning, I drove south with the windows slightly open, breathing in cold ocean air as the highway curved toward the coast. My phone remained quiet, and the silence felt unfamiliar but wonderful, like entering a house after years of hearing an alarm that never stopped ringing. I thought about the single word I’d sent my mother at 1:04 that Thanksgiving week, and how much my life had changed because I finally meant it. I hadn’t lost my family over $680,000; I had stopped losing myself to keep a family that only valued me when I was useful.
Legal Notice: This story is a work of fiction. Names, characters, businesses, events, and incidents are the product of the author’s imagination or are used fictitiously. Any resemblance to actual persons—living or dead—or to actual events is purely coincidental. Thank you! 💓