“Her Military Pension Is Worthless!” My Husband Told His Lawyer. The Lawyer Read The Beneficiary Clause, Then Requested The Original Documents. My Husband Had Been Showing Investors A Copy Naming Him As The Recipient Of My Death Benefits. I Produced The Current Designation. His Name Was Gone. The Lawyer Asked, “How Much Did You Borrow Against Money You’ll Never Receive?”
My husband called my military pension worthless while his parents watched me struggle to stand, and nobody defended me. When he demanded our house, my savings, and everything connected to his business, I quietly collected the papers he wanted me to sign. I didn’t argue or beg him to reconsider. Three weeks later, a woman from a private lending firm called about a financial guarantee I had supposedly authorized. She knew my military service history, my medical retirement date, and a beneficiary designation I hadn’t seen in eighteen months.
## Part 1: The Divorce Agreement That Was Supposed to Leave Me With Nothing
The first time my husband called my military pension worthless in front of a lawyer, he was wearing a $4,200 suit I’d helped pay for. He sat across a polished conference table on the thirty-ninth floor of a Denver office tower, examining his reflection in the dark glass of the window. Below us, traffic crawled along Speer Boulevard beneath a pale October sky, and somewhere behind the walls, an espresso machine hissed. Blake Ellison looked more comfortable than he had in our own house for months.
“Let’s stop pretending this is complicated,” he told his attorney. “Nora spent eight years moving supplies around for the Army, and now she gets a little government check because she can’t walk properly. That doesn’t make her a business partner.”
Martin Bell, the attorney sitting beside him, stopped arranging his legal pads. He was a narrow-faced man in his late fifties, with silver hair, rimless glasses, and a wedding ring that had worn a pale groove into his finger. He glanced at my cane leaning against the chair, then at the stack of financial disclosures between us. “Mr. Ellison,” he said carefully, “we’ve discussed how characterizations like that can complicate negotiations.”
Blake smiled. “I’m paying you to keep things uncomplicated.”
My own attorney, Celia Ward, sat beside me with a yellow legal pad balanced on her knee. She was forty-three, dressed in a navy blazer with one sleeve slightly frayed at the cuff, and she had already warned me that Blake would use the meeting to provoke an emotional reaction. I had told her he would probably start with my pension. Neither of us expected him to do it before anyone had offered coffee.
Blake pushed a document across the table with two fingers. “The house stays with me, obviously. Nora keeps her car, her personal belongings, and whatever military payments she’s entitled to receive. She signs away any interest in Northstar Relay and agrees that the company has no outstanding obligations to her.”
I opened the agreement, although Celia had already reviewed an earlier version. The proposed terms were worse than I remembered: Blake wanted our four-bedroom house in Colorado Springs, the balance of a savings account I had maintained before our marriage, and a release protecting him from any future claims related to the business. Buried near the end was a provision stating that I acknowledged all financial representations made during our marriage. I read that sentence twice.
“Why would I acknowledge financial representations I wasn’t involved in?” I asked.
Blake exhaled loudly. “Because we were married, Nora. That’s how marriage works.”
“Marriage doesn’t turn an unknown statement into an authorized one,” Celia replied.
Martin adjusted his glasses. “Let’s identify the specific concern before we characterize the provision.”
Blake leaned back, crossing his legs. “The concern is that my wife has suddenly decided she’s a financial expert because she looked at a couple of bank statements. Nora, you were good at following orders, and I respect that, but please don’t confuse that with understanding commercial financing.”
For a moment, I looked at the hands resting in my lap. There was a faint white scar across my right knuckle from a loading accident in Jordan and another near my wrist from a piece of shattered equipment in Syria. My left leg was beginning to ache, as it always did when I sat too long, but the pain had nothing to do with the pressure building behind my ribs. Three years earlier, I would have apologized simply to make him stop talking.
I had joined the Army at nineteen because college was expensive, my mother was dead, and my father’s small roofing business had collapsed during the recession. I spent eight years in uniform, eventually working in intelligence-supported logistics, coordinating supply movement through places where a delayed shipment could mean a field hospital running short of critical equipment. I wasn’t a spy or a decorated battlefield commander. Most days, my work involved manifests, satellite communications, vehicle maintenance reports, and identifying discrepancies before they became somebody else’s emergency.
At twenty-seven, an explosion near a supply staging area in northern Syria ended that career. I survived with a spinal injury, nerve damage in my left leg, and headaches that still appeared whenever the weather changed. Two people from our logistics team never came home, and I carried their names in places where no one could see them. The Army eventually determined that I could no longer meet the physical requirements of my position.
My medical retirement gave me a modest monthly income, access to medical care, and the possibility of building another life. It did not make me wealthy, and it certainly did not erase what I had lost. But it meant I had served long enough, and been injured badly enough, for the government to recognize an ongoing obligation to me. Blake treated that obligation like a charitable donation he found embarrassing.
When I returned to Colorado, he had been waiting outside the airport security doors with flowers and a navy-blue scarf. We’d met during one of my stateside assignments, and he had stayed in touch through deployments, sending photographs of snowstorms, restaurant menus, and the dog he promised we would someday adopt. He understood just enough about the military to sound sympathetic without knowing what my work actually involved. I mistook that for consideration.
He proposed six months after I came home. By then, I was desperate for a life where nobody checked the threat level before starting a vehicle, and Blake seemed to offer exactly that. He told me I had spent enough years carrying other people’s burdens. I married him believing we would finally carry our own together.
Our wedding was small, held at a mountain lodge outside Colorado Springs, with folding chairs, white roses, and a cake his mother complained was too plain. My sister, Tessa Moreno, stood beside me, smiling until she noticed that Blake had changed the reception seating without asking. He placed my former Army friends at the tables farthest from the family photographs. When she mentioned it, he said the business guests needed to be closer to the front because they had traveled farther.
I remembered that little decision as I studied the settlement agreement. It was the first time he had quietly informed me that his relationships mattered more than mine, and I had accepted the explanation because I wanted the day to be peaceful. Looking back, our marriage had been full of small administrative decisions that somehow always ended with Blake holding the paperwork. He handled the mortgage, the investments, the insurance, and eventually the passwords.
“Nora?” Celia’s voice brought me back to the conference room. “Do you want to respond to the proposed acknowledgment?”
I closed the agreement. “I’m not signing it.”
Blake’s expression hardened. “Then you’re wasting everyone’s time.”
“Possibly,” I said. “But I’d like Mr. Bell to review one document before we discuss my signature again.”
I opened the canvas portfolio resting against my chair and removed a sealed envelope. Inside was a current beneficiary confirmation, a benefits verification summary, and a comparison sheet prepared by my attorney from records we had obtained through authorized channels. Martin reached for the packet with a patient expression, expecting another argument about the value of my retirement income. Blake turned toward the window, already bored.
Martin examined the first page, moved to the second, and then returned to a paragraph near the bottom of the verification. His fountain pen, which had been tapping against the table, stopped moving. He read the attached schedule once, then again, holding it closer to the overhead light.
“Mr. Ellison,” he said, without looking at Blake, “I need you to answer a question about the capital you raised for Northstar Relay.”
Blake shrugged. “What about it?”
Martin’s voice had changed. “Did you represent your wife’s military death benefits as collateral for any of those loans?”
Blake stared at him as though the question were ridiculous. “Arthur at Apex Capital accepted the guarantee. Everybody understood the arrangement.”
Martin turned another page. “According to this record, your wife changed her beneficiary designation eighteen months ago, and the benefits you’re describing cannot be assigned to a business lender in the first place.”
Blake’s face went completely still.
I watched Martin place the document carefully on the table, and I understood that the one conversation Blake had spent months avoiding was finally happening without his permission.
## Part 2: The Marriage That Slowly Turned My Service Into His Property
To understand why Blake believed he could use my military benefits in a business negotiation, you have to understand the way he organized our marriage. He never demanded control in one dramatic conversation, and he never told me outright that he considered my life less valuable than his ambitions. Instead, he volunteered to handle one responsibility after another, presenting every new restriction as something he was doing to spare me unnecessary stress. By the time I noticed how much control I had surrendered, asking a simple question about our checking account could ruin an entire evening.
The changes began shortly after our honeymoon. Blake said our finances would be easier to manage if we consolidated our accounts under a system his accountant had designed. He showed me colorful spreadsheets, explained how our household could benefit from his company’s tax planning, and promised that my military retirement deposits would remain mine. I agreed to a joint account for household expenses but kept a separate savings account at a credit union I’d used since my first duty station.
For a while, everything seemed ordinary. Blake was building Northstar Relay, a software company that claimed it could help hospitals, emergency agencies, and medical suppliers track critical deliveries during disruptions. I liked the idea because I knew how easily a supply chain could fail when everyone believed someone else was responsible. Sometimes he asked me about inventory procedures or shipment prioritization, and I gave him practical suggestions without expecting anything in return.
Then he stopped describing my contributions as suggestions and began referring to them as things he’d taught me. At a dinner with prospective investors, he explained a tracking feature that closely resembled a system I’d helped improve during my deployment. When a woman from a hospital procurement group asked how he’d developed the concept, he put an arm around my shoulders and said, “Nora inspires me because she proves even the simplest procedures can be improved with real technology.” The table laughed politely, and I stared at the untouched salmon on my plate.
Later, in the parking garage, I told him the remark had embarrassed me. He opened the passenger door of his leased Mercedes and said I was being overly sensitive. “These people understand sophisticated systems,” he explained. “They don’t need a ten-minute conversation about military shipping labels.” I wanted to tell him that the shipping labels he found amusing had sometimes been the only thing separating usable medical supplies from dangerous mistakes, but he was already starting the engine.
His mother, Patricia Ellison, reinforced that attitude. She was a retired real estate broker who could identify the price of someone’s handbag from across a restaurant and considered public reputation a form of currency. Every Thanksgiving, she introduced Blake as an entrepreneur and me as his wife who was “recovering from the military.” If anyone asked about my service, she redirected the conversation toward Blake’s next funding round.
His younger brother, Grant, was kinder in private but rarely spoke when their mother was present. Once, after Patricia joked that Blake had married me for the government health coverage, Grant quietly asked whether I needed help carrying my bag to the car. I said I was fine because the question itself made me feel exposed. He looked toward the dining room and apologized for her behavior, but he returned inside without confronting her.
By our second anniversary, Blake had begun asking me to sign financial documents that arrived in thick overnight envelopes. Some were ordinary forms concerning our mortgage or his company’s insurance arrangements, but others included limited powers of attorney, estate-planning acknowledgments, and declarations about federal benefits. He always approached me when I was tired, often after physical therapy, setting the papers beside my dinner plate with yellow stickers marking the signature lines. If I wanted to read everything, he acted disappointed.
One evening, I found an authorization form granting broad access to my financial and insurance information. Blake said his accountant needed it to prepare our taxes, but the document covered subjects that had nothing to do with tax preparation. I crossed out the sections concerning beneficiary changes and independent borrowing authority before signing the narrower permission. He stared at the corrections and asked whether I believed he was planning to steal from me.
“I believe I should understand what I’m signing,” I replied.
He collected the papers without another word. For the next two days, he communicated through short text messages about groceries and appointments, leaving the house before breakfast and returning after I had gone upstairs. When he finally began talking normally again, I was so relieved that I didn’t ask whether his accountant had accepted the revised authorization. That was how our disagreements usually ended: I made a reasonable request, and he made the atmosphere so unpleasant that I eventually regretted speaking.
Eighteen months before the divorce meeting, I visited a military benefits counselor after a routine appointment. A woman in the waiting room had been struggling to correct an outdated beneficiary designation following her mother’s death, and the conversation reminded me that I had not reviewed my own records since getting married. Blake was listed on an older group life insurance election, made when our marriage still felt safe. I decided to review everything while I was already there.
The counselor explained the differences between my retired pay, any survivor arrangements, and the separate life insurance coverage I’d maintained. These were not interchangeable benefits, and none functioned as a guaranteed commercial asset that a spouse could pledge to investors. After discussing my circumstances and the procedures applicable to each benefit, I changed the beneficiary on my military group life coverage to my sister, Tessa. I also arranged for an estate attorney to review how any proceeds could help Tessa care for her son, Milo, who had been born with a serious hearing impairment.
I did not tell Blake immediately. By then, I had stopped mentioning administrative errands unless they directly affected our household, largely because he turned even minor decisions into debates about my judgment. Tessa knew about the change and asked whether everything was all right at home. I told her I was simply making sure my affairs reflected my wishes, which was true but incomplete.
Around the same time, Blake became unusually interested in my injuries. He asked whether my medical retirement could ever be reversed, whether periodic evaluations affected my income, and whether life insurance companies treated deployment-related disabilities differently. Initially, I thought he was concerned about our long-term financial security. Then he began asking questions about what Tessa would receive if something happened to me.
“Why do you keep asking?” I said one Sunday while washing breakfast dishes.
“Because I’m the one planning for our future,” he answered. “Somebody has to think about the unpleasant possibilities.”
He kissed my forehead and left a folder on the counter labeled FAMILY PROTECTION. When I opened it later, I found photocopies of old insurance elections and a handwritten worksheet calculating the projected value of various survivor payments over twenty years. Several figures were exaggerated or based on assumptions that did not apply to my circumstances. A note in Blake’s handwriting said, “Estimated federal backing: $1.8M.”
I asked him about the number that evening. He laughed and said it was an insurance-planning exercise, not actual money sitting in an account. The explanation was plausible enough that I returned the folder to his desk, but I photographed the worksheet first. I had spent too many years reconciling missing inventory to ignore an unexplained figure that large.
Six months before our separation, Blake began coming home after midnight. He blamed investor negotiations, complicated contracts, and a difficult product launch, but I noticed that the garage trash contained shredded copies of documents bearing my name. His office door acquired a new lock, and his mother started calling during dinner to ask whether I’d been sorting through his business materials. I hadn’t mentioned the office to her, which meant Blake had.
Then one Thursday morning, while Blake was attending a technology conference in Austin, my credit union called to confirm an inquiry from a commercial lending company. The employee said no loan had been opened in my name, but the inquiry included enough personal information to make her concerned. I asked for the lender’s identity and wrote it down on the back of an envelope.
The name was Apex Capital Partners. It appeared on the same handwritten worksheet where Blake had estimated my federal benefits at $1.8 million.
That afternoon, I opened the family safe and found a signed document I had never seen before.
## Part 3: The Locked Safe Contained More Than Our Marriage Could Survive
The safe was a waist-high steel cabinet tucked into the alcove behind Blake’s office bookshelf. We had purchased it together after a small wildfire threatened several neighborhoods outside Colorado Springs, and my passport, military records, and the title to my car were supposed to be stored inside. Blake had gradually filled it with company binders and started keeping the key on his own ring. I still had the spare key from the day we installed it.
I opened the cabinet expecting to find financial trouble. Blake had recently sold his motorcycle, delayed a kitchen renovation he’d been discussing for months, and canceled a trip to California without explaining why. I thought Northstar Relay might be running out of money, and I wanted to understand whether our mortgage was at risk. Instead, the first binder I removed had my full name printed beneath the words CONTINGENT GUARANTEE PACKAGE.
Inside were copies of my discharge papers, disability retirement records, old insurance beneficiary information, and summaries of federal programs that had been assembled to look like a single transferable financial asset. Someone had highlighted the words “government administered” and “survivor” throughout the packet. An introductory page described an estimated $1.8 million in federal-backed proceeds available upon a qualifying event, with Northstar Relay named as the intended recipient through Blake’s supposed authority as my husband. Nearly every important assertion on that page was misleading or false.
The next section was worse. A document titled SPOUSAL CONSENT AND COLLATERAL ACKNOWLEDGMENT carried a signature that resembled mine, dated during a week when I had been receiving inpatient rehabilitation treatment. The handwriting was close enough to fool someone glancing at it, but the final letter of my surname curved in a way I had never written. My signature was followed by a notary stamp from a county I had not visited that year.
I sat on the office floor with the binder open across my knees. The room smelled of furniture polish and overheated electronics, and the only sound was the periodic click of the heating system. My leg had begun to tremble, so I shifted against the wall and examined the document again. I recognized the source of the signature immediately: Blake had copied it from the authorization form I’d carefully edited at the kitchen counter.
The realization was difficult to absorb because it involved more than money. Someone had taken an act of trust, a signature I provided for a limited household purpose, and transformed it into permission for a transaction I would never have approved. Blake had not merely concealed financial losses. He had manufactured the appearance of my consent.
I photographed the documents, recorded their order, and called Celia Ward, whose name Tessa had given me several months earlier after another argument about finances. Celia practiced family law but worked closely with financial litigation attorneys, and she agreed to meet me the following morning. Her first instruction was to preserve what I had found without altering the original records. Her second was to avoid discussing the discovery with Blake until we understood the scope of the problem.
At Celia’s office, I explained what the packet claimed to guarantee. She listened without interruption, occasionally asking for dates or the names of institutions. When I reached the fabricated consent form, she put down her pen and said, “Nora, this is no longer just a question of marital property.” She asked whether Blake had ever obtained my consent to pledge a life insurance interest, and I told her he had never even asked.
We brought in a commercial finance attorney named Daniel Cho, who had spent years representing creditors before moving into fraud litigation. He explained that federal military benefits are governed by different rules, and a private business cannot simply convert them into assignable collateral by attaching photocopies to a loan application. The $1.8 million figure was not an actual guaranteed payout; it appeared to combine a genuine life insurance limit, invented indemnity provisions, and the projected lifetime value of benefits that would never be payable as a commercial lump sum. Even if Blake had remained my beneficiary, his collateral representations would have raised serious legal problems.
“Why would a lender accept something this questionable?” I asked.
Daniel studied the cover page. “Sometimes the person selling a story is more convincing than the person checking it. Sometimes a lender is desperate to make a deal work, and sometimes someone inside the transaction has another reason to look away.” He paused over the name of Apex Capital’s account executive. “What concerns me is that this packet looks designed to satisfy a checklist rather than withstand scrutiny.”
The binder contained three separate funding schedules. Apex Capital had advanced $410,000 to Northstar Relay, a private investment group called Brighton Ridge had supplied another $320,000, and a smaller credit facility accounted for the rest. The combined exposure approached $940,000, not including interest or various fees. Blake had signed personal guarantees on at least two of the agreements.
I asked whether the lenders could come after our house. Daniel explained that the answer depended on the actual contracts, the ownership records, state law, and whether any valid liens existed. He would not promise that my property was automatically protected simply because Blake had lied. Instead, he recommended preserving evidence, reviewing our marital finances, checking recorded property documents, and taking steps to protect my accounts and identity.
For the first time in years, someone was answering my questions without treating them as insults. Celia contacted the appropriate benefits administrators with me, and we obtained current confirmation of my life insurance designation and retirement information. We separately consulted the benefits counselor about the rules governing survivor arrangements, because those could not be treated as interchangeable with life insurance. I also placed protections on my credit files and changed access credentials for accounts held solely in my name.
Blake returned from Austin that Sunday carrying a glossy conference tote and a bottle of expensive olive oil he claimed had come from a restaurant investor. He found me preparing chicken soup and asked whether I’d missed him. I said the house had been quiet, which was true, and he kissed my cheek before checking his phone. Ten minutes later, he was in the basement office with the door shut.
Over the next several weeks, Celia’s team reconstructed the movement of money through our household accounts. The mortgage had been paid regularly, but several transfers Blake described as temporary business expenses had never been repaid. My savings account was intact because I had refused to merge it completely, although he’d repeatedly pressured me to contribute more. His own supposed wealth consisted largely of assets purchased with borrowed money.
Then Daniel found something the safe hadn’t shown us. Northstar Relay had been telling investors that it served regional hospitals through a pilot project involving veterans’ medical transportation and emergency supply distribution. The company’s public materials included photographs of volunteer drivers, mobile clinics, and donation events. I recognized one of the photographs from a fundraiser Patricia had hosted, where she insisted the entire family wear matching blue ribbons.
The fundraiser supported a nonprofit called Homeward Reach, which claimed to help injured veterans obtain transportation and medical equipment. Patricia sat on its board, and Blake supplied technology services through Northstar Relay. I had volunteered at two events, sorting donated winter clothing and helping visitors fill out service referral forms. At the time, the organization seemed modest, earnest, and badly in need of administrative help.
Daniel showed me a vendor invoice bearing my initials beside an approval stamp. It authorized payment from Homeward Reach to Northstar Relay for logistics software implementation. The date was from a Saturday when I’d attended Milo’s school recital in Pueblo, and the amount was $68,500. My initials looked as though somebody had copied them from another document.
I stared at the invoice until the numbers blurred. Blake had used my military background to sell his company’s credibility, and then somebody had apparently used my identity to justify taking money from a nonprofit serving people like me. The financial problem was no longer contained within our marriage. It reached into a community that had trusted the same story I once believed.
Two days later, a former Northstar Relay employee left a message on my voicemail.
“My name is Evelyn Price,” she said. “I used to handle the books, and I need you to know your husband didn’t start using those documents when the company got into trouble. He was preparing them long before you got married.”
## Part 4: The Former Bookkeeper Revealed Why My Husband Had Chosen Me
Evelyn Price agreed to meet at a diner on the outskirts of Monument, halfway between Colorado Springs and Denver. She was sixty-two, with cropped gray hair, reading glasses hanging from a cord, and the exhausted appearance of someone who had rehearsed an uncomfortable conversation too many times. She ordered hot tea and left the bag in the cup until the water turned almost black. Before she said anything about Blake, she asked whether I had brought a lawyer.
Celia sat beside me in the booth. “I’m here to understand what you’re willing to share,” she said, “and to make sure Nora doesn’t inadvertently become responsible for handling materials she shouldn’t possess.” Evelyn nodded, reached into her canvas purse, and took out a handwritten chronology rather than a folder of company records. She had spent the previous week checking dates against her own employment notes and the public filings Daniel had sent through the proper channels.
“I worked for Blake before Northstar had a product anyone could use,” she began. “The original company was called Meridian Route, and it existed mostly as presentations and bills. He was a charming young man with a good idea, but he spent money as though investors were already lining up outside his door.” Evelyn stirred her tea without drinking it. “When the first company failed, he didn’t accept that the numbers were wrong; he decided the people evaluating them hadn’t understood his vision.”
Blake had hired her again when he formed Northstar Relay. According to Evelyn, he initially talked about creating affordable routing software for rural medical networks, a goal she considered worthwhile. Then he began pursuing venture funding, and the product demonstrations became more polished while actual customer installations remained scarce. She repeatedly warned him that revenue projections needed to be separated from signed contracts.
“I wasn’t surprised when he started courting investors through military connections,” she said. “What surprised me was how quickly he learned to make your service history sound like a corporate asset.”
The sentence landed harder than I expected. Blake had told me he admired my resilience, and when I struggled with rehabilitation, he had appeared genuinely frightened for me. I had treasured those moments because they were evidence that someone saw more than the injuries. Now I wondered how much he had seen and how much he had calculated.
Evelyn turned one page in her notes. “Before your wedding, he asked me whether federal military insurance could be pledged as business collateral. I told him I wasn’t qualified to answer, and our outside accountant said the same thing. He came back a week later with a consultant who claimed there were specialized arrangements available for veterans with certain service histories.” She paused. “I never saw a legitimate opinion supporting what he eventually did.”
I asked whether Blake had already been planning to use my benefits when he proposed. Evelyn looked uncomfortable, and for a moment I thought she would avoid answering. Instead, she said she’d seen an early Northstar funding presentation with a section titled “Founder Household Stability.” It described my expected retirement income, medical coverage, and projected insurance benefits as factors reducing the company’s financial risk.
“Did he mention me by name?” I asked.
“Yes,” Evelyn said. “The presentation was dated three weeks before your engagement.”
My stomach tightened, but Celia rested one hand on the table and asked Evelyn to continue. The document alone did not prove Blake had married me for financial reasons, and Evelyn was careful about distinguishing what she knew from what she suspected. Still, his early financial planning showed that my future husband had been treating my military service as an investment consideration before we ever exchanged vows.
I remembered the evening he proposed. We were standing on a wooden overlook above a reservoir, and Blake had dropped to one knee so awkwardly that I laughed before I began crying. He said he’d never met anyone who made the world feel manageable. I had thought he meant my steadiness and the ordinary pleasure of being together. Now I couldn’t stop wondering whether he also meant the dependable deposit arriving in my bank account each month.
Evelyn explained that Patricia’s nonprofit had become part of Northstar’s marketing strategy. Homeward Reach needed scheduling help, and Blake offered his software at what he called a preferred charitable rate. Public donation campaigns raised money for transportation assistance, adaptive equipment, and emergency travel expenses. Meanwhile, Northstar billed the nonprofit for software development, integration, and support services that Evelyn couldn’t always match to completed work.
“When I asked for proof of delivery, Blake said the government contracts would cover the cost later,” Evelyn told us. “When I asked why the nonprofit was paying first, he accused me of not understanding startup cash flow.” She eventually discovered that several billing approvals attributed to volunteers had not been obtained from those volunteers. My initials appeared among them.
I wanted to ask why she hadn’t reported everything immediately, but her expression stopped me. She had been caring for a husband with kidney disease, and Northstar had been her main source of income after another employer closed its local office. She told us she’d initially believed the missing documentation could be corrected. When she finally refused to process another invoice without supporting records, Blake terminated her employment and claimed she had mishandled confidential information.
“I should have done more,” she said. “I know that.”
I looked at her hands, which were folded so tightly that the skin around her knuckles had turned white. “I wish someone had told me earlier,” I replied, “but I’m glad you’re telling me now.” It was the most forgiveness I could offer without pretending that the silence hadn’t mattered. Evelyn accepted it with a small nod.
After the meeting, Celia contacted counsel for Homeward Reach’s independent board members. The nonprofit was legally separate from Northstar, and any investigation of its finances needed to be handled by people with appropriate authority. We provided information that could be verified without circulating sensitive medical records or proprietary files. A few days later, the organization’s treasurer requested an independent financial review.
Blake noticed the change almost immediately. He came home one evening to find me reviewing our household expenses at the kitchen table and asked why Patricia had received questions about nonprofit invoices. I said I had heard concerns about the organization and wanted to understand them. He demanded to know whom I’d been speaking with, and when I refused to discuss other people’s conversations, he accused me of undermining the only work that had given our family any real standing.
“You’ve been sitting in this house judging me for years,” he said, bracing his hands against the counter. “You have no idea what it takes to build something.”
“I know what it takes to keep something operating after a mistake,” I answered. “The first step is admitting there’s a problem.”
He stared at me for several seconds. Then he said, “Maybe we should stop pretending this marriage is worth saving.”
I had imagined hearing those words would make me desperate. Instead, I felt a strange lightness beneath the fear, as though a door I’d been leaning against had finally opened. I told him I would speak with my attorney, and he laughed at the idea that I had one.
Within a week, divorce papers arrived. Blake asked the court to award him the house and declare Northstar Relay his separate business interest, while also seeking broad releases from future marital claims. He presented himself as the financially responsible spouse supporting a disabled veteran who had contributed little to their standard of living. Patricia supplied a written statement describing my supposed inability to understand household finances.
I read her statement in Celia’s office, recognizing the same polished phrases Patricia used at her charity events. She had not merely remained silent while Blake humiliated me. She was now willing to put her contempt into a document that could affect my future.
Then Celia turned to the last page of Blake’s financial disclosures. Northstar Relay had recently drawn another $175,000 from Brighton Ridge, using a renewed collateral certification dated after my attorney had begun requesting records. The certification represented that all previously pledged security remained valid and unchanged.
Blake had renewed his false guarantees while preparing to divorce the woman whose benefits supposedly supported them.
And the attorney representing him was about to see what those guarantees were actually worth.
## Part 5: The Beneficiary Clause That Exposed Nearly a Million Dollars in Lies
On the morning of the settlement conference, I woke before my alarm and found Blake’s last written offer sitting on the kitchen counter. He had sent it through his attorney the previous afternoon, giving me forty-eight hours to accept before he pursued what he called a more aggressive legal strategy. The document demanded almost everything we owned together while disclaiming any responsibility to me for Northstar Relay’s finances. Beside it, I placed an old photograph of myself in uniform, taken before the explosion, and tried to remember when I had begun believing his description of me.
Celia arrived at eight with coffee and a slim leather briefcase. She reviewed our plan while I finished putting on my boots, reminding me that the meeting was an opportunity to establish the disputed facts, not to force an immediate settlement. We had already produced appropriate financial disclosures and notified the relevant administrators about the suspected misuse of my records. Today, Martin Bell would receive the authenticated materials necessary to compare Blake’s representations with the current federal records.
“He’s going to try to make this personal,” Celia warned.
“It already is,” I answered.
She studied my face for a moment. “Then remember that you don’t have to prove your worth to him. We need to establish what happened, who authorized it, and what obligations actually exist.”
The drive to Denver took just over an hour. The foothills were covered with yellow cottonwoods, and the morning sun flashed across windshields as traffic slowed near Castle Rock. I kept my hands wrapped around a paper coffee cup while Celia drove, occasionally feeling the familiar pressure of my left knee beneath the dashboard. I had attended military briefings where the consequences of an error were measured in lives, but the prospect of sitting across from my husband still made my stomach tighten.
Blake was already waiting when we entered Martin Bell’s office. He stood beside the window with his phone in one hand, wearing a charcoal suit and the watch he’d purchased after Northstar announced its first major financing agreement. He greeted Celia with an exaggerated smile, then looked at my plain jacket and orthopedic boots. “I see we’re dressing for the occasion,” he remarked.
Martin invited everyone to sit. He had prepared several settlement drafts, and the largest binder contained Blake’s financial disclosures, including valuations for our home and his ownership interest in Northstar. I noticed that Martin’s copy of the records was neatly arranged, unlike the chaotic documents Blake usually left scattered around our house. For a moment, I wondered how much of the truth had been concealed from the man whose name appeared on the legal correspondence.
Blake began by explaining why he deserved the house. He claimed his business income had supported the mortgage, repairs, utilities, and most of our daily expenses. He omitted my contribution to the original down payment, several household transfers from my separate account, and the fact that his supposed income frequently consisted of shareholder distributions funded by business borrowing. Celia asked him to identify the source of those payments, and he responded with a theatrical sigh.
“Nora’s pension barely covers groceries,” he said. “I’m the one who built our life.”
I had heard the sentence so many times that it no longer surprised me. What hurt was the certainty with which he repeated it, even though we’d spent months gathering records that contradicted him. He was not simply remembering our marriage differently. He was counting on everyone in the room accepting his version because he delivered it with more confidence.
When Martin asked whether we had objections to the proposed asset division, Celia presented our financial analysis. She identified my documented contribution to the down payment, the disputed marital transfers, and the need for an independent valuation of Northstar. Blake interrupted twice, insisting that military retirement payments gave me sufficient security and that any further distribution would reward me for doing nothing. Martin reminded him to let Celia finish.
Then Celia opened the benefits packet.
“Before we address the release language,” she said, “we need to discuss several representations your client appears to have made concerning Nora’s federal benefits and insurance coverage.”
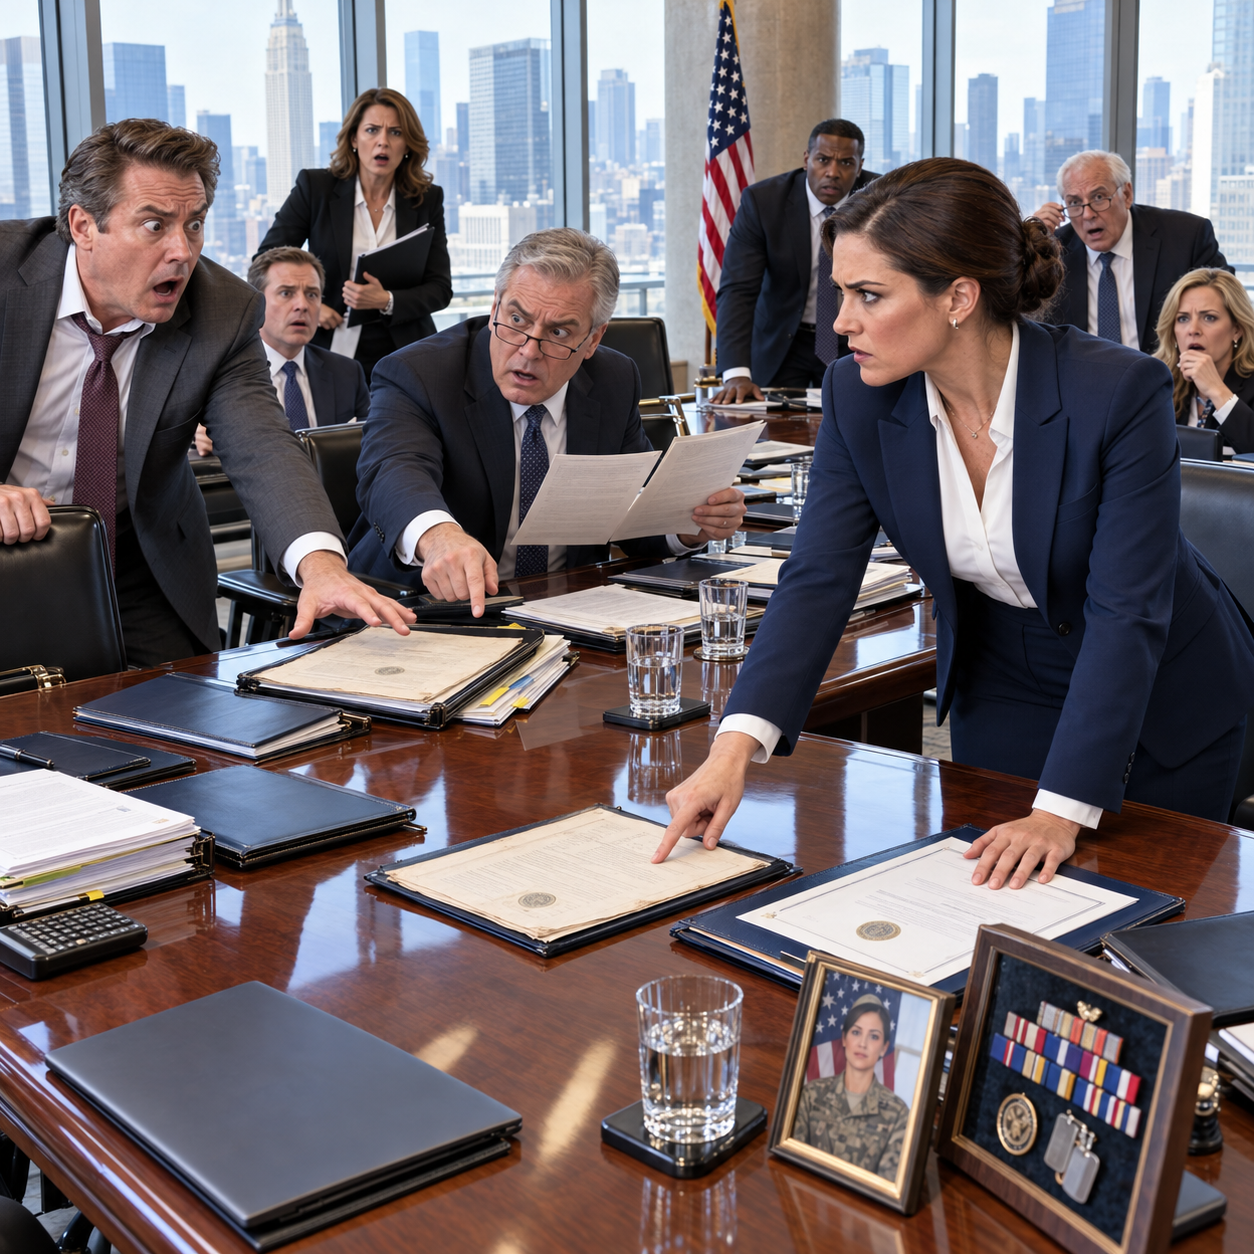
Martin took the documents and began reading. The first pages confirmed the distinction between my military retired pay, applicable survivor provisions, and the group life insurance coverage I maintained. The following pages established that my current life insurance beneficiary designation had been recorded eighteen months earlier. The packet also included a comparison prepared from the collateral representations Northstar had produced during financial discovery.
At first, Martin’s expression remained neutral. Then he reached the section identifying the supposed beneficiary-backed guarantee and asked Celia to clarify the source of the accompanying commercial language. She explained that it came from Northstar’s own financing documents, not from any federal administrator. Martin turned back to the current designation, following the printed information with one finger.
“Mr. Ellison,” he said, “did you represent that Northstar would receive proceeds from your wife’s military insurance if she died?”
Blake shrugged. “There was a survivor arrangement. Arthur at Apex said the funding structure was acceptable.”
“Did you represent that you were the beneficiary?”
“At the time, yes.”
Martin looked at him. “At which time?”
Blake sat forward. “When we put the original financing together.”
“The renewal certification was executed recently,” Martin replied. “This beneficiary designation was changed eighteen months ago, and the documents describe benefits that cannot lawfully be pledged in the manner represented.”
Blake turned toward me. “You changed it?”
“Yes.”
“Without telling me?”
“It was my designation to review, and I followed the applicable procedures.”
His expression shifted from outrage to calculation. “Then change it back. We can settle everything once you correct the problem.”
Celia spoke before I could answer. “There is no valid reason for Nora to name your client as a beneficiary to support an unauthorized commercial obligation. Even that would not make the rest of these representations accurate.”
Martin set down his fountain pen. He examined the renewal certification, compared the signatures, and then asked whether Blake had personally executed the financing applications. Blake admitted that he had signed them but said his company’s former bookkeeper handled the supporting documentation. Martin’s jaw tightened when Celia mentioned that some documents contained signatures whose authenticity was disputed.
“How much outstanding capital is secured or purportedly supported by this package?” Martin asked.
Blake rubbed his forehead. “About six hundred thousand, depending on how you calculate it.”
Celia slid the lender schedule across the table. “The disclosed commitments, including the most recent draw, are substantially higher.”
Martin read the numbers and closed his eyes briefly. “Blake, we need a private conversation before this negotiation continues.”
Blake stood so abruptly that his chair rolled backward. “This is absurd. My own wife is trying to destroy a company she knows nothing about.”
I looked at him across the table. “I asked you about that $1.8 million figure two years ago. You told me it was only a planning exercise.”
“Because you wouldn’t have understood the explanation.”
“Then explain why my signature appears on a collateral acknowledgment dated while I was in rehabilitation.”
He opened his mouth but said nothing. Martin rose, gathered the documents, and led Blake into an adjoining office. Through the glass partition, I could see my husband pacing while his attorney stood beside a cabinet with his arms folded. Neither man looked in our direction.
The meeting did not end with an instant divorce decree or a dramatic confession. Martin returned twenty minutes later and announced that the proposed settlement would be withdrawn pending further review. He declined to discuss privileged conversations with his client, but he confirmed that the financial representations required examination by appropriate counsel. Blake left through a side exit without looking at me.
Celia began gathering our papers, and I felt a wave of relief so powerful that I had to remain seated. For months, Blake had framed every challenge to his authority as evidence that I was confused, ungrateful, or incapable. Now another professional had examined the same records and recognized the problem without needing me to raise my voice.
As we reached the elevator, Celia’s phone rang. It was Daniel Cho, calling with news from Homeward Reach’s independent financial review. The nonprofit had discovered that several transportation and equipment grants had been paid out on paper but never reached the veterans approved to receive them.
One of the missing payments was for a medically necessary wheelchair-accessible van modification. The veteran who had been promised that assistance had spent the previous month missing rehabilitation appointments because the money was gone.
## Part 6: The Missing Charity Money Revealed a Betrayal Older Than Our Marriage
The veteran’s name was Samuel Keene, a fifty-six-year-old former Army mechanic living outside Pueblo. He had applied to Homeward Reach for help modifying his van after an injury left him dependent on a wheelchair. According to the nonprofit’s records, his application had been approved, the funding had been allocated, and a payment had been sent to a service provider. The service provider, however, had never received the money.
I learned those details from the charity’s independent board representative rather than from Samuel himself. The review team was careful about privacy and did not give me access to his medical information beyond what was necessary to understand the problem. I knew enough to realize that a spreadsheet entry labeled COMPLETED could hide a real person still waiting beside a vehicle they couldn’t use. I had seen that kind of administrative deception overseas, usually when supply reports failed to match what was physically available.
Over the next month, a forensic accounting firm hired by Homeward Reach traced more than $180,000 in questionable payments to Northstar and related vendors. Some invoices described legitimate services but carried unsupported amounts, while others appeared to represent work that had not been performed. A portion of the money moved through a consulting company controlled by Patricia Ellison. The nonprofit’s independent directors suspended further payments to Northstar and referred the findings to legal counsel and the appropriate authorities.
Patricia called me the morning after the suspension became public within the organization. I was sitting at my dining table sorting medical bills when her name appeared on my phone. I almost ignored it, but Celia had advised me to preserve relevant communications, so I answered and made a note of the time. Patricia began speaking before I had finished saying hello.
“You need to stop this,” she said. “Blake is under enough pressure without you turning a routine accounting matter into a public scandal.”
“Homeward Reach has its own board,” I replied. “I don’t control its investigation.”
“Don’t insult my intelligence, Nora. You spoke with Evelyn Price, and now everybody is asking questions about paperwork from years ago.”
I looked out the window toward the maple tree in our front yard. “Did you know my initials were used to approve payments I never authorized?”
There was a pause. Then Patricia said, “You never appreciated what Blake was trying to accomplish. He gave you a respectable life when you came home with nothing but problems.”
The words were so practiced that I wondered how often she’d said them when I wasn’t present. I remembered pushing donated clothing racks into place at her fundraisers, carrying boxes despite the pain in my leg, and answering questions from veterans who needed help understanding referral forms. Patricia had smiled for photographs beside me and described our family as committed to serving those who had served. Now she spoke as though I’d been an inconvenience she had tolerated for appearances.
“You knew those payments weren’t authorized,” I said.
“I knew Blake needed flexibility to get the company established. That’s not the same thing.”
“People were promised assistance they didn’t receive.”
“Businesses sometimes have cash-flow problems.”
I ended the call after telling her that any further discussion should go through counsel. For several minutes, I sat without moving, listening to the refrigerator compressor cycle on and off. My anger wasn’t explosive; it was a heavy, sick feeling that settled beneath my ribs. Patricia had revealed that, even when confronted with missing charity funds, her first concern was protecting Blake.
Daniel’s investigation into Northstar’s finances uncovered another problem. The newest Brighton Ridge loan had not been used for the product development expenses stated in its funding request. Bank records showed transfers to cover overdue liabilities, payments to the related consulting company, and distributions that did not match the company’s reported financial condition. Those discrepancies mattered independently of the fraudulent military-benefit guarantee.
Apex Capital and Brighton Ridge each retained separate counsel to evaluate their exposure. Once they reviewed the inconsistencies, they requested additional documents and suspended further funding. Eventually, notices of default and demands for repayment followed, based on the loan agreements’ specific provisions. The numbers were devastating, but they did not become legally collectible from me merely because I had been married to Blake.
That distinction required work. Daniel and Celia reviewed our mortgage, property records, household transfers, and every guarantee produced during discovery. They sought to establish that I had neither authorized the commercial borrowing nor benefited from the diverted funds in the way Blake claimed. We could not make his creditors disappear, but we could challenge attempts to impose responsibility based on forged signatures and false statements.
Blake responded by accusing me of sabotaging his financing. In a message sent through his attorney, he claimed that changing my beneficiary designation had destroyed the security supporting Northstar’s loans. Daniel answered by explaining that my group life insurance had never been validly pledged as ordinary commercial collateral, and that the false certifications had originated with Northstar. The resulting financial consequences came from the company’s own representations and transactions.
A week later, someone left a cardboard box on my front porch. Inside were photographs from our wedding, several unopened birthday cards, and the scarf Blake had given me when I returned from deployment. There was no note, but I understood the message. He was trying to reduce three years of marriage to a collection of sentimental objects while our attorneys examined evidence of financial misconduct.
I brought the box inside because rain was coming. Tessa arrived that afternoon with Milo, who immediately asked whether he could have the empty cardboard box to build a garage for his toy trucks. I gave it to him after removing the photographs, and he spent an hour cutting doors into the sides while Tessa helped him tape the roof. Watching them work in my living room felt more comforting than anything Blake had said to me in months.
When Milo went into the kitchen for a snack, Tessa asked what I planned to do with the wedding pictures. I told her I hadn’t decided, and she said I didn’t have to turn every painful object into a lesson immediately. She knew I was spending my evenings sorting evidence, answering attorney emails, and preparing for another round of financial disclosures. “You can put them in a closet,” she said, “and still be someone who knows what happened.”
That evening, Grant Ellison knocked on my door. He looked thinner than he had at Thanksgiving and held a manila envelope against his chest. I invited him into the kitchen but didn’t offer any reassurance about the family situation. He accepted a glass of water, then told me Patricia had asked him to sign a statement defending Blake’s management of Homeward Reach.
“I didn’t sign it,” he said.
“Why not?”
“Because I remembered something.”
Grant explained that, before my wedding, Patricia had held several private meetings with Blake about financing. At one of them, Grant had been asked to help prepare presentation materials for a potential investor. The slides described Northstar’s market opportunity, its expected contracts, and a financial risk profile supported by Blake’s future spouse’s military benefits. Grant had assumed the information was authorized because Blake spoke about it openly.
“I thought you knew,” he said, placing the envelope on the table. “I thought it was part of some estate plan you’d agreed on.”
The envelope contained an old presentation and a printed email from Blake to Patricia. The message referred to my upcoming marriage as an opportunity to strengthen Northstar’s financial profile. It was dated nine days before Blake took me to the reservoir and asked me to become his wife.
At the bottom, Patricia had replied, “Make sure she feels secure. Once the paperwork is finalized, the rest will be easier.”
I read the sentence three times before I could look at Grant. He was staring at the kitchen floor, ashamed of his family’s conduct but unable to undo the years he’d spent avoiding it. I thanked him for bringing the documents and told him my attorney would need to review their authenticity and relevance.
After he left, I sat at the table where Blake used to place forms beside my dinner plate. The room was quiet except for the clock above the stove, and the scarf from the airport lay in the box near my feet.
For the first time, I allowed myself to consider that Blake hadn’t merely exploited our marriage after falling into financial trouble. He might have entered it with a financial purpose already in mind.
## Part 7: The Courtroom Where My Husband Finally Had to Answer for Himself
Our divorce did not proceed as quickly as Blake had promised his investors. The original settlement conference had exposed questions neither side could responsibly ignore, and the subsequent financial review took months. By February, Northstar had lost its remaining credit facilities, several vendors were pursuing unpaid invoices, and the company had reduced its staff to a handful of employees. Blake continued insisting that his business would recover if everyone stopped interfering.
Meanwhile, Celia prepared for a contested hearing concerning property, financial disclosures, and the authenticity of the documents supposedly bearing my authorization. Independent examiners compared the disputed signatures with known samples, and their findings supported our position that several had been copied or imitated. The notary associated with one acknowledgment reported that her seal had appeared on a document she had not notarized. These facts became part of the evidentiary record rather than something I was expected to resolve through another argument with my husband.
The hearing took place in a courthouse with worn wooden benches and fluorescent lights that made everyone look tired. I arrived early with Celia and found a seat near the front, placing my cane against the bench. Blake entered with a new attorney, a younger man named Steven Hale, whose dark suit fit well but whose expression suggested he understood the difficulty of the case. Martin Bell had withdrawn from representing Blake after the breakdown of settlement negotiations, following the required professional procedures.
Patricia sat two rows behind her son. She wore a cream-colored coat and held a leather handbag in her lap, looking around the room as though attending a tedious appointment. Grant was present too, but he took a seat on the opposite side. When our eyes met, he gave me a small nod.
The judge first reviewed the disputed financial disclosures. Celia presented records showing my contribution to the house, the transfers from our household accounts, and the separate ownership of my long-standing savings. She also established that Northstar’s value could not be determined from Blake’s optimistic presentations when its debts, defaults, and questionable transactions were taken into account. Blake’s attorney challenged portions of the analysis, but the underlying records were difficult to explain away.
Blake testified that he had carried most of our household expenses because my retirement income was modest. He described me as emotionally withdrawn after my military service and suggested that our disagreement arose from my inability to adapt to civilian business life. When Celia asked whether he’d ever consulted me before using my records in financing packages, he claimed that our marriage included an understanding that he would manage financial matters. He could not identify a valid document granting the authority he described.
Celia then asked about the collateral acknowledgment. Blake said he believed his company had followed ordinary procedures and that outside consultants prepared the supporting materials. He admitted signing the loan certifications but maintained that he had relied on advice concerning the value of the supposed guarantees. When asked why he’d renewed those representations after learning that the beneficiary information was outdated, he paused long enough for the courtroom to become uncomfortable.
“I assumed the underlying protection remained available,” he finally answered.
“But you had already been informed that the designation had changed?”
“Yes.”
“And you were aware your wife disputed the authenticity of the acknowledgment?”
“She was making a lot of accusations.”
Celia let him finish before asking whether a spouse’s disagreement made an unauthorized signature valid. Blake looked toward his attorney, who could offer no testimony for him. He eventually said no, barely above a whisper.
I watched the exchange with less satisfaction than I had expected. For months, I imagined seeing him forced to acknowledge what he’d done, but there was nothing pleasurable about observing someone dismantle his own credibility one answer at a time. I had loved him, trusted him with my recovery, and imagined growing old in the house we shared. Those memories remained real even though the promises behind them had not been kept.
My own testimony centered on records and decisions I could describe firsthand. I explained the nature of my military service, the circumstances of my retirement, and the beneficiary changes I’d made through the proper channels. I also described the limits I’d placed on the financial authorization Blake had given me and the documents I’d found afterward. Celia had helped me organize the chronology so I could answer questions without being drawn into every painful memory.
When Blake’s attorney asked why I hadn’t confronted my husband immediately after discovering the records, I explained that I wanted independent advice before accusing anyone of financial wrongdoing. I had been concerned about losing access to evidence and about protecting myself from debts I did not understand. More importantly, I had learned during my service that making a serious accusation without verifying the facts could harm innocent people. The judge listened without interrupting.
Patricia’s statement about my supposed financial incompetence received considerably less attention than she’d apparently expected. Celia questioned its foundation, pointing out that Patricia had no direct knowledge of many household transactions and was personally connected to a company receiving payments from Homeward Reach. Her involvement in those transactions was being examined separately. The judge declined to treat her opinions about my intelligence as meaningful evidence concerning property ownership.
During a recess, I found Patricia waiting near the drinking fountains. She approached while Celia was speaking with Daniel and asked whether we could talk privately. I refused to step away from the public hallway, so she stood beside me and lowered her voice. “You could have settled this quietly,” she said. “A family shouldn’t do this to itself.”
“I offered Blake several opportunities to provide accurate records,” I replied.
Patricia looked toward the courtroom doors. “His company is finished. Do you understand what you’ve cost him?”
I felt the familiar pressure in my chest, but I did not turn away. “He signed those documents. He took the loans. He approved payments that couldn’t be supported, and people who needed help went without it.” I shifted my cane into my right hand. “You can be angry with me for finding out, but that doesn’t change who made those decisions.”
She stared at me, perhaps expecting the apology I had once offered whenever our conversations became uncomfortable. When none came, she walked away. I never received another direct call from her.
The court’s final decisions came after further review and negotiation. The marital home was awarded to me under a property settlement that accounted for our respective contributions, the disputed transactions, and Blake’s obligations, with the necessary transfer and financing arrangements handled through counsel. My separate savings remained mine, and the decree did not impose Northstar’s commercial obligations on me. Blake retained his business interests subject to their actual liabilities rather than the inflated values he had previously claimed.
The divorce became final in early spring. By then, creditors had begun pursuing Northstar and Blake under the relevant agreements, and separate investigations into financial representations and the nonprofit transactions were continuing. Those proceedings had their own standards and timelines, and I did not control their outcomes. I was simply relieved that my future no longer required his permission.
A few days after the decree was entered, Blake sent a handwritten letter to my attorney. He asked Celia to pass it along, explaining that he wanted one last conversation before he moved out of Colorado Springs. Celia told me I was not obligated to respond, and I asked her to send me a copy.
The letter began with an apology for the way he had spoken about my military service. By the second paragraph, however, he was explaining how investors had pressured him, how Evelyn had misunderstood financial procedures, and how his mother had encouraged him to maintain appearances. He wrote that he had never intended to hurt me and hoped we might eventually remember the good years.
I reached the last sentence and understood what was missing. Blake wanted forgiveness for the consequences of his choices, but he still could not describe those choices without assigning part of the responsibility to someone else.
I folded the letter, put it in the file containing our divorce documents, and told Celia there would be no meeting.
## Part 8: I Kept the House, Rebuilt My Life, and Left His Regrets Behind
The first morning after Blake removed the last of his belongings, I woke at five twenty and listened to the heating system settle. The house was quiet in a way I had never experienced while we were married. There was no shower running upstairs, no phone vibrating on the kitchen counter, and no expectation that I would need to judge someone’s mood before making breakfast. I walked downstairs slowly, put coffee in the machine, and opened the blinds facing the backyard.
Blake had taken his suits, office furniture, electronics, and the framed award Northstar received at a regional business conference. He left behind several empty shelves and a patch of lighter paint where his oversized company logo had hung in the basement. I had planned to convert that room into storage, but when I stood there with a tape measure in my hand, I realized I wanted it to become something entirely different. I wanted a workspace that belonged to me.
I had taken occasional contract assignments in logistics planning after my medical retirement, mostly projects I could complete remotely. During the divorce, an emergency management coordinator named Rachel Benton had asked whether I would be interested in reviewing supply distribution procedures for rural communities during wildfire season. She knew my military background through a former colleague, not through Blake, and our first conversation lasted nearly two hours. For once, someone was interested in what I understood rather than what could be extracted from my records.
Rachel eventually offered me a part-time consulting role assisting a regional emergency preparedness network. The pay was reasonable, the hours accommodated my medical appointments, and the work involved practical problems I knew how to solve. I reviewed warehouse inventories, transportation backups, and communication procedures for situations when roads became inaccessible. My first recommendation was almost embarrassingly simple: require independent confirmation when a shipment was marked delivered.
Rachel laughed when I explained it. “You wouldn’t believe how often people assume a computer entry means somebody actually received something,” she said.
“I would,” I answered.
The work gave my days a structure that did not depend on Blake’s ambitions. I set up a desk facing the basement window, hung a map of Colorado on the wall, and bought an inexpensive whiteboard for planning schedules. Tessa brought over a lamp she found at a thrift store, and Milo insisted on placing a small plastic truck beside my monitor for good luck. The room smelled of fresh paint for weeks.
I also began volunteering with a veterans’ transportation organization that had no connection to Homeward Reach. I didn’t join its board or take on responsibilities I couldn’t sustain. Instead, I helped review scheduling procedures and volunteered a few hours each month to make sure drivers had accurate addresses, contact information, and pickup requirements. After watching what happened when those details were ignored, I found genuine satisfaction in making ordinary systems more reliable.
Homeward Reach underwent significant changes. Its independent directors removed individuals connected to the questionable transactions, strengthened financial oversight, and worked with donors and service providers to address documented unmet obligations. Some of the missing money was recovered through negotiated repayments and civil proceedings, although not every loss could be made whole immediately. Samuel Keene eventually received assistance through a separate program, and I learned about it from a public update rather than any confidential record.
I was glad when I heard he’d gotten the help he needed. The news did not erase the months he’d spent waiting or the appointments he’d missed. It also reminded me that Blake’s misconduct had consequences beyond our marriage, affecting people who never knew his name. The personal humiliation I’d suffered was painful, but it was no longer the largest part of the story.
By late summer, Northstar Relay had ceased operations. Its remaining assets were handled through formal creditor proceedings, and several civil claims resulted in financial judgments and negotiated repayment obligations. Blake’s personal guarantees left him exposed to substantial debt, while the disputed collateral documents became part of broader legal scrutiny. The authorities handling the related investigations did not share every detail with me, and I stopped trying to interpret silence as an indication of what might happen next.
Eventually, the public record showed that Blake had entered a plea agreement concerning fraudulent commercial financing representations. The court imposed restitution obligations and other penalties, and the consequences were far more serious than simply losing his company. I read the available documents once, checked that my identity was accurately described in the relevant records, and put them away. I did not attend the sentencing to watch him suffer.
Grant called a few weeks later. He said Blake had moved into a small rented apartment and was attempting to find work unrelated to company financing. Patricia had stepped away from her charitable activities, and their extended family was arguing over who had known what and when. Grant sounded exhausted, though he did not ask me to reconcile with anyone.
“I should have said something years ago,” he told me.
“Yes,” I replied. “You should have.”
He accepted the answer. We spoke for another few minutes about his job and his plans to move closer to his daughter in Fort Collins. I wished him well before hanging up, and for the first time, I felt no need to soften the truth to keep someone else’s family comfortable.
Blake made one final attempt to contact me that autumn. He sent a letter to the address of my attorney, acknowledging that he’d used my records without proper authorization and that he’d made false statements because he was desperate to keep Northstar operating. Unlike his earlier letter, this one contained no complaints about investors or suggestions that my actions had caused his downfall. He said he understood if I never wanted to see him again.
I believed he regretted what had happened. I even believed that he might finally understand some part of the damage he’d caused. But regret did not restore the trust he’d systematically dismantled, and understanding arrived too late to make another relationship possible. I asked Celia to retain the letter with the other records and send a brief acknowledgment that I did not wish to have further contact.
That decision surprised a few people. A neighbor who had known us as a couple suggested that surviving such a difficult experience together might eventually make us stronger. She meant well, and I knew she had not seen the forged documents or watched the nonprofit’s financial records unravel. I told her that Blake and I had not survived the same experience together. He had created a problem, and I had spent months protecting myself and others from its consequences.
There were still difficult days. My leg hurt during cold weather, physical therapy remained part of my schedule, and I sometimes woke from dreams that had nothing to do with my marriage. I continued meeting with a counselor who understood military transitions and the complicated grief of losing a relationship that had once felt like safety. Recovery was not a dramatic moment of triumph; it was a collection of habits that made ordinary life manageable again.
One Saturday in November, Tessa convinced me to visit an animal rescue outside town. I had mentioned wanting a dog but worried about handling a large animal with my mobility limitations. The rescue coordinator introduced me to several calm adult dogs and eventually brought out a golden retriever mix named Cooper, who had been surrendered after his owner entered assisted living. Cooper approached slowly, sniffed my cane, and settled beside my chair without demanding attention.
I sat with him for twenty minutes while Tessa asked questions about his temperament and health. When I stood to leave, he rose and followed me to the gate, looking back once to make sure I was still there. I returned the next weekend with the completed adoption paperwork. Cooper came home wearing a blue collar and spent his first evening asleep on the rug beneath my desk.
By the time the following spring arrived, the house felt different. I had replaced the heavy office curtains with lighter ones, planted herbs beside the back steps, and turned the unused formal dining room into a place where Milo could spread out his art supplies. Friends visited without worrying whether Blake would interrupt them with a business pitch. Tessa sometimes stayed late, and we ate takeout while Cooper slept beneath the table.
On the anniversary of my retirement, I drove to a veterans’ memorial garden near Colorado Springs. I brought two small flowers for the people I’d lost in Syria and spent an hour walking slowly between the engraved stones. I thought about the younger woman who’d stepped off a military transport believing that the hardest part of her life was behind her. She had been exhausted and injured, but she’d also been hopeful, and I no longer wanted to remember her as foolish for trusting someone.
My service had taught me to verify information, care for people depending on me, and take responsibility when something went wrong. Those were ordinary principles rather than secret weapons, and they had helped me survive a marriage built on increasingly dishonest assumptions. I hadn’t needed to become wealthy, powerful, or famous to protect myself. I had needed accurate records, competent help, and enough confidence to stop accepting another person’s version of my life.
That evening, I returned home just before sunset. Cooper met me at the door with his leash in his mouth, and I took him into the backyard where the grass was beginning to recover from winter. The maple tree had new leaves, the kitchen windows glowed in the fading light, and my phone sat inside on the counter without a single message I was afraid to read.
For years, Blake had treated my pension as proof that I was worth less than he was. He thought a monthly benefit was a measure of my ambition, my intelligence, and my place in our marriage. When his business began collapsing, he tried to turn that same benefit into a financial guarantee, as though every part of my life existed to keep his plans alive. The contradiction became impossible to hide once someone finally examined the documents.
I kept the home I had helped purchase, the savings I had protected, and the freedom to decide what happened next. Blake’s debts and legal troubles remained his responsibility, just as the choices that created them had been his. I no longer followed reports about his attempts to rebuild his reputation, and I did not need to hear that he was unhappy to feel satisfied with the outcome.
Before going inside, I sat on the back step and watched Cooper explore the far corner of the yard. My leg ached, so I stretched it carefully and rested my coffee mug beside me. Through the open window, I could hear the dishwasher running and Milo laughing at something Tessa had said.
I thought about the divorce conference, the old beneficiary records, and the moment Martin Bell realized that the financial structure supporting Blake’s confidence was largely fiction. I had entered that room expecting another fight over whether my years in uniform counted for anything. What emerged instead was evidence of decisions my husband had made long before the marriage ended.
I never forgave Blake for using my trust against me, and I never invited him back into my life. I didn’t need his apology, his admiration, or his eventual understanding to make peace with what had happened.
When Cooper finally came back and laid his head against my knee, I scratched behind his ears and looked toward the house.
For the first time since leaving the Army, I had a future that belonged entirely to me.
THE END!
Disclaimer: Our stories are inspired by real-life events but are carefully rewritten for entertainment. Any resemblance to actual people or situations is purely coincidental.