My Parents Gave My Sister Our Family Home—Then the Bank Called About a $286,000 Loan Bearing My Signature
My parents handed my younger sister the keys to our childhood home while thirty relatives applauded, then thanked me for being “the one who never needed help.” Three mornings later, a bank called to ask about a $286,000 refinance I supposedly signed years earlier. I had been hundreds of miles away on the date printed beneath my name. What began as a humiliating family celebration became an investigation into missing money, a secret agreement, and the person who knew exactly how my signature got there.
Part 1
The brass keys made a bright little sound when Dad dropped them into my sister’s palm. Thirty relatives crowded our childhood backyard outside Columbus, Ohio, with paper plates on their knees and grilled corn smoking nearby. “Beth and Gabe are going to raise Lucy here,” Dad announced. Everybody clapped except Grandma Esther and me.
I’m Mara Whitcomb, thirty-six, a risk analyst who notices details other people skip. Mom had invited me to a “simple family lunch” and asked me to bring lemon cake; Beth had known for weeks she was getting the house. Her in-laws brought champagne, and a banner already read WELCOME HOME, SLOANS. Apparently I was the only one who hadn’t rehearsed my reaction.
I didn’t expect my parents to give me their property. What stung was Beth’s expression when she spotted me holding the cake carrier. “Don’t be weird about it,” she said. “You have your townhouse and career; we have a child.” Six-year-old Lucy chased bubbles nearby, innocent of the comparison.
Mom cornered me in the kitchen beside lemonade glasses. “Beth needs stability, and you’ve always taken care of yourself,” she said. That was our family arithmetic: when Beth needed something, I understood; when I needed something, I managed. Dad had lost his manufacturing job years earlier, and I’d paid property taxes, bought a furnace, helped repair their roof, and rescued Beth from overdue rent.
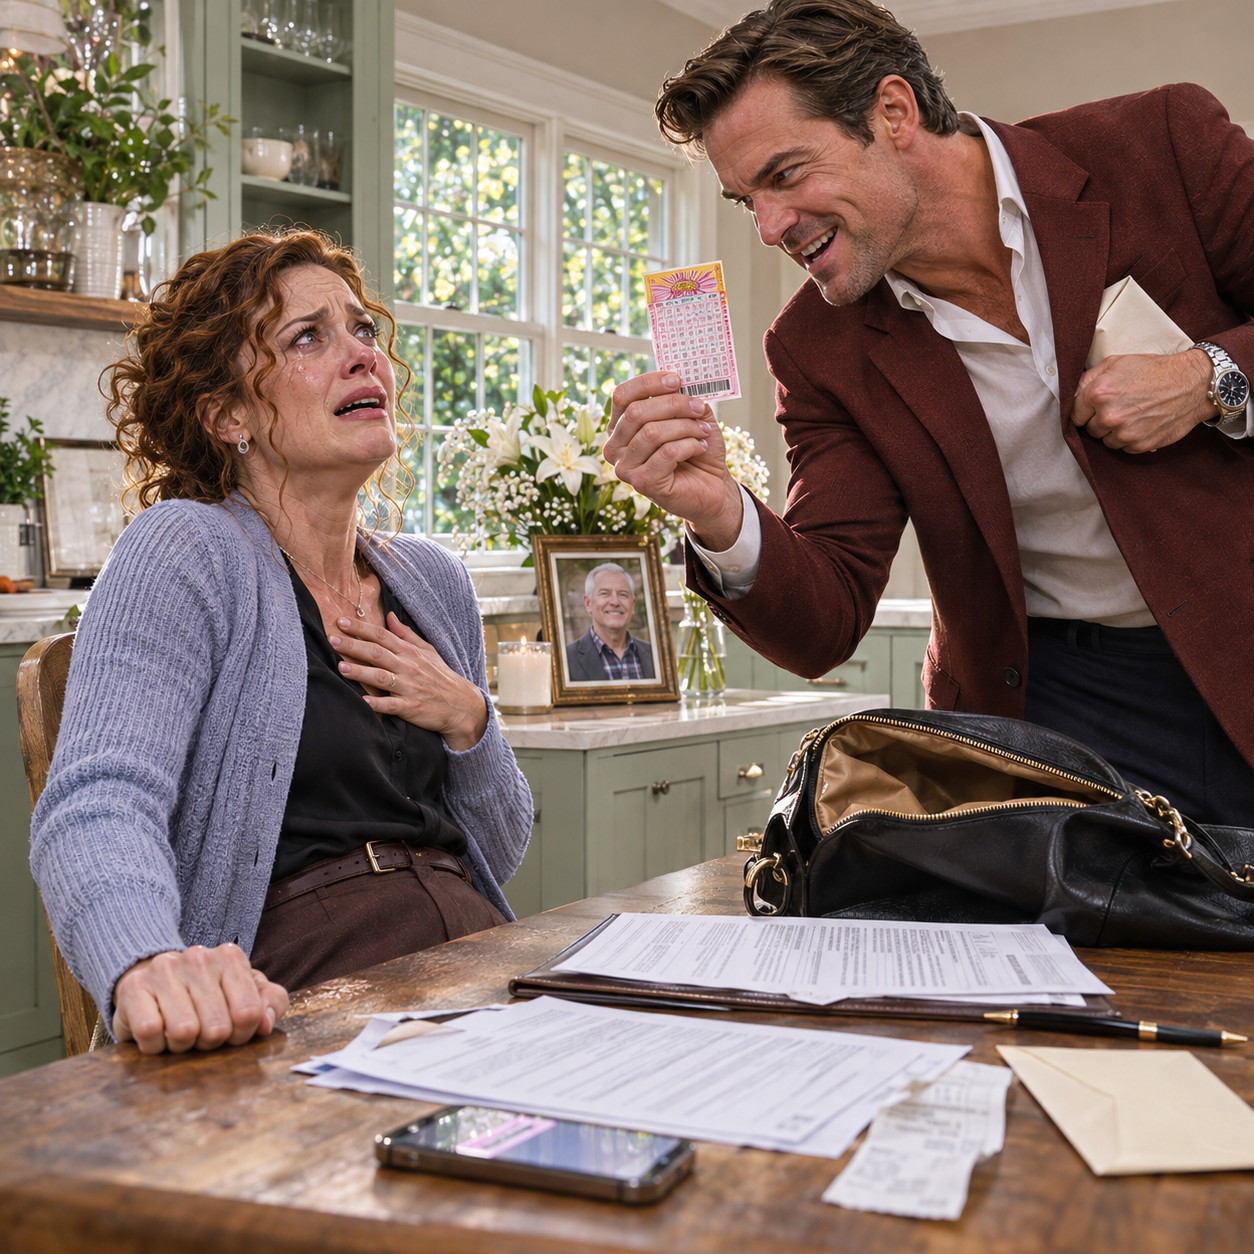
I never considered those gifts investments, but as Dad carried chairs inside, I asked, “Is there a mortgage on the house?” His shoulders stiffened. “That’s between your mother and sister. Stop turning a happy day into an audit.” Grandma Esther, a retired bookkeeper, watched silently from the doorway.
On the drive home, Esther asked how much I’d paid toward the house. “Forty thousand, maybe,” I guessed. She said Dad had requested another seventy-five thousand from her in 2018, promising I’d cover the difference if she refused. “Make sure they’re giving away something they actually own,” she warned.
Tuesday morning, my phone rang in the office parking garage. “Naomi Shah, Harbor First Bank,” the caller said. “We’re reviewing a refinance application on 48 Sycamore Lane. Can you confirm the agreement you signed in 2018?” I stopped beside a concrete pillar; Sycamore Lane was my parents’ address.
“I never signed one,” I said. Naomi described a file containing my income, driver’s license, and three signatures attributed to me in connection with a $286,000 mortgage. My parents were the recorded borrowers, but a supporting agreement named me. One signature was dated September 28, 2018, and the certificate said I’d appeared before an Ohio notary; I’d spent that day at a conference in Denver.
I wrote down everything she said. The new transfer to Beth had triggered review because the title file showed an unresolved claim in my name. At the bank, Naomi showed me a scanned signature that almost looked real, except its capital W had a loop I’d never used. Somebody had attached my identity to the house without asking.
Then she showed me a page titled FAMILY CONTRIBUTION AND REPAYMENT AGREEMENT. “We don’t yet have the complete attachment,” she explained. Beneath my purported signature, the correspondence address was not my townhouse but a post office box belonging to Dad’s old tool business. I remembered using his printer for tax forms in 2017 and felt my stomach sink.
Back home, I studied the mortgage settlement summary. The 2018 refinancing had released more than $118,000 in cash, but only a fraction had gone toward debts Dad claimed were threatening them. Three weeks after the closing, Beth and Gabe had purchased their first house. I stared at those dates until they rearranged into a question I didn’t want to ask.
Where had my sister’s down payment really come from?
Part 2
I took the documents to Simone Price, a real estate attorney whose office smelled of printer toner and peppermint tea. She examined the signatures and asked whether I’d ever authorized anyone to act for me. “No power of attorney, no remote signing, no phone call,” I said. Simone tapped the notary certificate. “Then we’ll prove where you were.”
My employer’s archived badge and travel logs placed me in Denver throughout September 28, 2018. I had paid for dinner there at seven-thirty, although the supposed certificate said I’d appeared before an Ohio notary at 3:15 p.m. I forwarded everything to Simone. Before I could call Dad, he called me.
“Your mother says you’re upset about Beth getting the house,” he began. I asked whether my name appeared on his old refinancing documents. After a pause, he said, “You helped us back then. Sometimes people forget what they agreed to.” I wrote down that sentence and replied, “I remember exactly where I was.”
Mom invited me to Sycamore Lane two days later. Moving boxes lined the hall, and Beth sat with Gabe while Dad pushed a three-page affidavit toward me. It said I acknowledged the 2018 transaction, released all property claims, and consented to giving Beth the house. A pen waited across the signature line, like the decision had already been made.
“You’re asking me to certify something I never did,” I said. Dad called it a technicality, and Mom asked why I’d punish Lucy over paperwork. Beth muttered that I hated seeing her get ahead. I left without signing, and Simone obtained the archived six-page agreement the next day.
It claimed I’d contributed $71,600 to the family home and that my parents owed me $108,000 upon another sale, refinance, or below-market transfer. The signatures were fake, but the document created a supposed financial interest that the new title insurer wanted resolved. Dad needed me to release an obligation invented to support the old transaction. The lie had survived until it became inconvenient.
“Why forge paperwork saying they owe me money?” I asked, and Simone showed me lender notes presenting me as a reliable source of continuing support. My income and past payments helped explain my parents’ finances, although I wasn’t a borrower on the mortgage. The fake agreement made that support look officially approved. Whoever designed it had counted on my never checking.
Grandma Esther visited with old checks from when she’d refused Dad’s request for money. “He said once the refinance cleared, Beth would finally be secure,” she remembered. Simone found a matching thread in the settlement ledger: about $32,000 paid listed debts, while $43,000 went to an escrow account bearing Beth’s married surname, Sloan. The balance went into my parents’ checking account.
I remembered Beth boasting that she’d saved her down payment by skipping vacations. I remembered Dad praising her discipline while I covered his property taxes. Suddenly I wasn’t embarrassed by how much I’d given; I was furious about how they’d used it. The purpose of the refinance had been bigger than saving the house.
The bank suspended Beth’s new loan while investigating. Dad called, accusing me of making Lucy homeless, although the house still legally belonged to him and Mom. I asked who signed my name, and he said, “Dates and signatures get mixed up.” Then he added, “Don’t make me explain things you won’t like.”
An hour later, Simone emailed a photograph of the retired notary’s journal. The entry named only Thomas and Diane Whitcomb, with six chilling words alongside: THIRD SIGNATURE PRESENT BEFORE MY ARRIVAL. I had evidence I never attended the signing, but who in that house had held the pen?
Part 3
The retired notary, June Carver, met us at a diner smelling of bacon and furniture polish. “Your parents brought the form with your name already on it,” she told Simone. She’d notarized their signatures, but the certificate mistakenly implied I’d been present. She admitted she should have corrected it and agreed to provide a sworn statement.
Simone found Lewis Baird, the attorney who drafted the agreement. He’d never met me, relying on Dad’s assurances that I consented. Weeks after closing, someone claiming to be me had phoned his office, and the return number belonged to my parents’ house. Lewis’s old handwritten note required direct confirmation from me before any future transaction. Dad had been warned.
That evening Mom left a voicemail. “Nobody meant to take anything from you,” she said over the television. “We were desperate, and you always said you’d help.” I saved it, noticing how carefully she chose “meant to,” as if good intentions could authenticate a signature. Simone told me to preserve every message instead of confronting them alone.
Beth called the next morning, her turn signal ticking through the conversation. “You’ve frozen my future because you’re mad about the house,” she snapped. I explained the bank had suspended the transaction because of unauthorized paperwork. “You didn’t complain when their money got us started,” she replied. When I asked what money she meant, she hung up.
Her old purchase file answered. It contained a $43,000 gift letter Dad had signed, declaring the funds his savings and requiring no repayment. The money had actually come from the Sycamore Lane refinance. I remembered Gabe thanking Dad for a “little closing help,” unaware of the source. Beth hadn’t simply benefited from that year; she’d helped disguise it.
I drove past Sycamore Lane that afternoon. The dogwood Dad planted when I started kindergarten was rust-red, and the porch rail I’d helped paint still had a white drip near the steps. I wanted to remember that house as a home rather than collateral. I drove on without stopping, afraid that even my memories had been edited for somebody else’s comfort.
An archived underwriting email arrived Monday. The lender had asked Dad to obtain direct confirmation from me; he’d replied that I traveled too much to take calls. Minutes later Mom emailed a scanned signature page from their home computer, writing, “Mara has reviewed everything and wants us to keep the house.” I hadn’t reviewed a word.
Dad requested a private meeting the next afternoon. The brass keys lay on the kitchen table beside hard green pears. “What would settle this?” he asked, offering $20,000 if I’d sign the release and raising it to $35,000 when I refused. I said I wanted the truth, not a price.
“Where would the money come from?” I asked, mentioning the possibility of another loan using my name. Dad called me ungrateful and said being part of the family had paid me back. I walked out and summarized the exchange for Simone. It was the last conversation in which I asked him for honesty expecting he might give it.
That evening, the bank’s counsel found a handwritten note dated two days before the 2018 closing. Mom’s handwriting was unmistakable. “Mara can’t find out about the $43,000 for Beth,” it said. “If she knows, she won’t agree to anything.” I read the next sentence and felt the last warm corner of my childhood go cold.
“Make sure Beth understands why Mara’s signature stays between us three.” Mom had sent the false paperwork, Dad had arranged the transaction, and Beth had known enough to stay quiet. When Mom texted an invitation to a “private family conversation,” I replied, “Sunday works.”
Part 4
“Private” meant thirteen relatives seated in my parents’ living room, including Beth’s in-laws. Dad had placed the brass keys beside a plate of sugar cookies and told everyone I was confused about an old refinance. “Mara’s always been sensitive about money,” he said sadly. Grandma Esther raised one eyebrow from across the room; she knew the performance.
Dad said I’d agreed to support their mortgage, then turned bitter because Beth needed the home more. Mom dabbed her eyes and asked us to put family first. Beth stared at the carpet while Gabe twisted his wedding ring. I waited until Dad finished, then asked where I’d supposedly signed.
“It was years ago,” he answered. I laid my Denver records on the table, followed by June Carver’s statement and Lewis Baird’s warning. Dad insisted the notary had mistaken the date, even though my signature was there before my parents arrived. He stopped smiling but repeated that everyone knew I would’ve helped.
Next came the settlement ledger and Beth’s $43,000 gift letter. “Part of the refinance bought Beth’s first home,” I said. Gabe turned toward his wife, asking when she’d learned the source. Beth whispered that she’d known before their closing but believed Dad had settled everything with me, yet when I asked why she hadn’t checked, she had no answer.
I placed Mom’s handwritten note on the table and read the line about hiding my signature. Aunt Renee lowered her cookie, and Mom’s crying stopped when I asked whether she’d written it. “Yes,” she whispered, then admitted, “I signed your name. Your father said the lender needed the paperwork completed, and you would eventually understand.”
“Did you think I’d refuse if you asked permission?” I said, and Mom nodded. Dad called my questions cruel, insisting I’d always paid when the family needed me. “What difference would your signature make?” he demanded. I finally understood what the word strong had meant to them: available, unquestioning, and easy to spend.
“The difference is that I decide what I give,” I answered. Gabe placed the brass keys in front of Dad and said they weren’t taking the house. Beth nodded after a long silence. I didn’t comfort her; she’d known about the money while I struggled to keep our parents’ bills paid. Her embarrassment belonged to her.
The bank’s review continued after that afternoon. It corrected the disputed supporting-party information after examining the original records, while my parents remained responsible for their mortgage. The proposed transfer was withdrawn, and Simone negotiated settlement of the contested repayment claim without saying I’d authorized any forged document. Legal problems don’t vanish because someone cries in a living room.
Six months later, my parents paid me $94,000 from their own assets and financing that didn’t involve my identity. The agreement preserved my denial of every signature attributed to me. I stopped paying their property taxes and emergency repairs. Mom kept apologizing with “but we had no choice,” until I stopped answering.
Beth sent a letter after she and Gabe rented a smaller place. She said she hadn’t understood how badly her silence would hurt, though she’d understood enough to take the money. I replied that I wished Lucy well, but had no interest in rebuilding our relationship. Dad sent nothing except a request that I stop telling relatives the story.
Two years later, Sycamore Lane sold to a couple planning a garden. Esther arranged for a nursery to grow a sapling from the old dogwood, and I planted it behind my townhouse on a cool Saturday. Soil darkened my fingernails, and my back ached pleasantly when I finished. It was the first piece of that property I wanted to keep.
That evening, I sat on the steps with iced tea and watched its leaves move in the breeze. My parents had handed my sister keys to a house they’d preserved using my identity without my permission. I didn’t forgive them or need them to understand why. For the first time, I owned something they couldn’t borrow, sign away, or announce to a crowd: my right to say no.
Legal Notice: This story is a work of fiction. Names, characters, businesses, events, and incidents are the product of the author’s imagination or are used fictitiously. Any resemblance to actual persons—living or dead—or to actual events is purely coincidental. Thank you! 💓