My Father Demanded Half My Salary for My Brother—Then the Bank Manager Opened My File
“My brother has children, so my father announced that half my paycheck belonged to him.” I was thirty-three, worked sixty-hour weeks, and had already paid for more family emergencies than I could count. At dinner, Dad lifted his glass while my brother celebrated his new income. I simply nodded. Two days later, they visited the bank expecting to claim my salary. The manager opened a restricted file and asked a question that wiped the smiles off their faces. They had no idea how long I’d been preparing for that moment.
Part 1
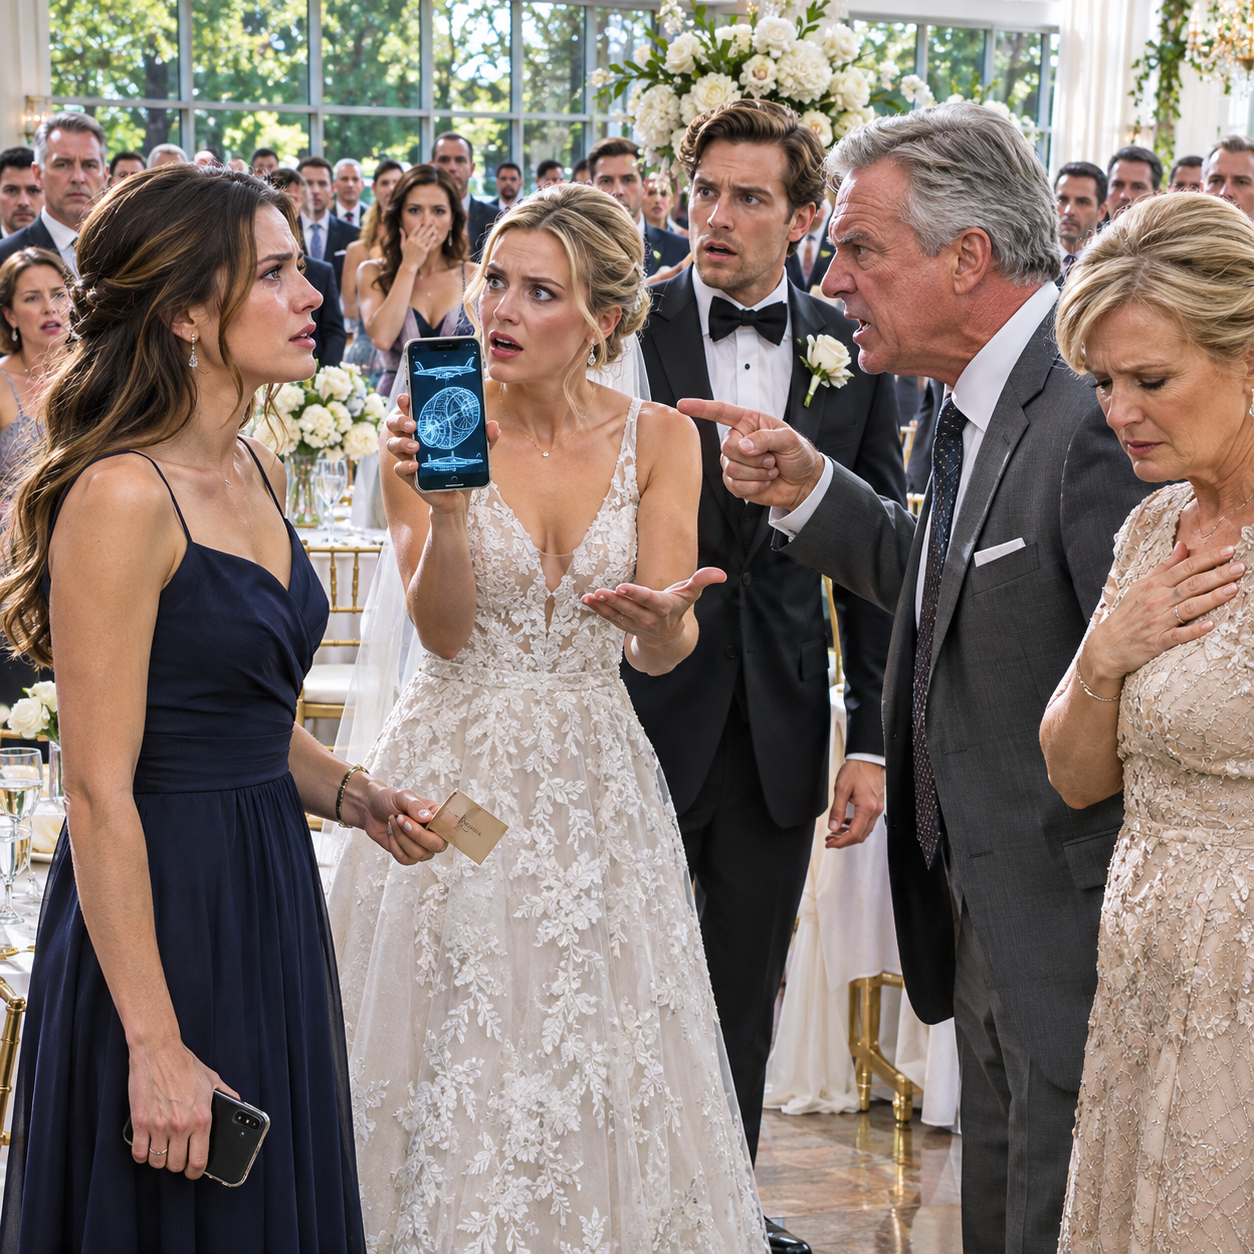
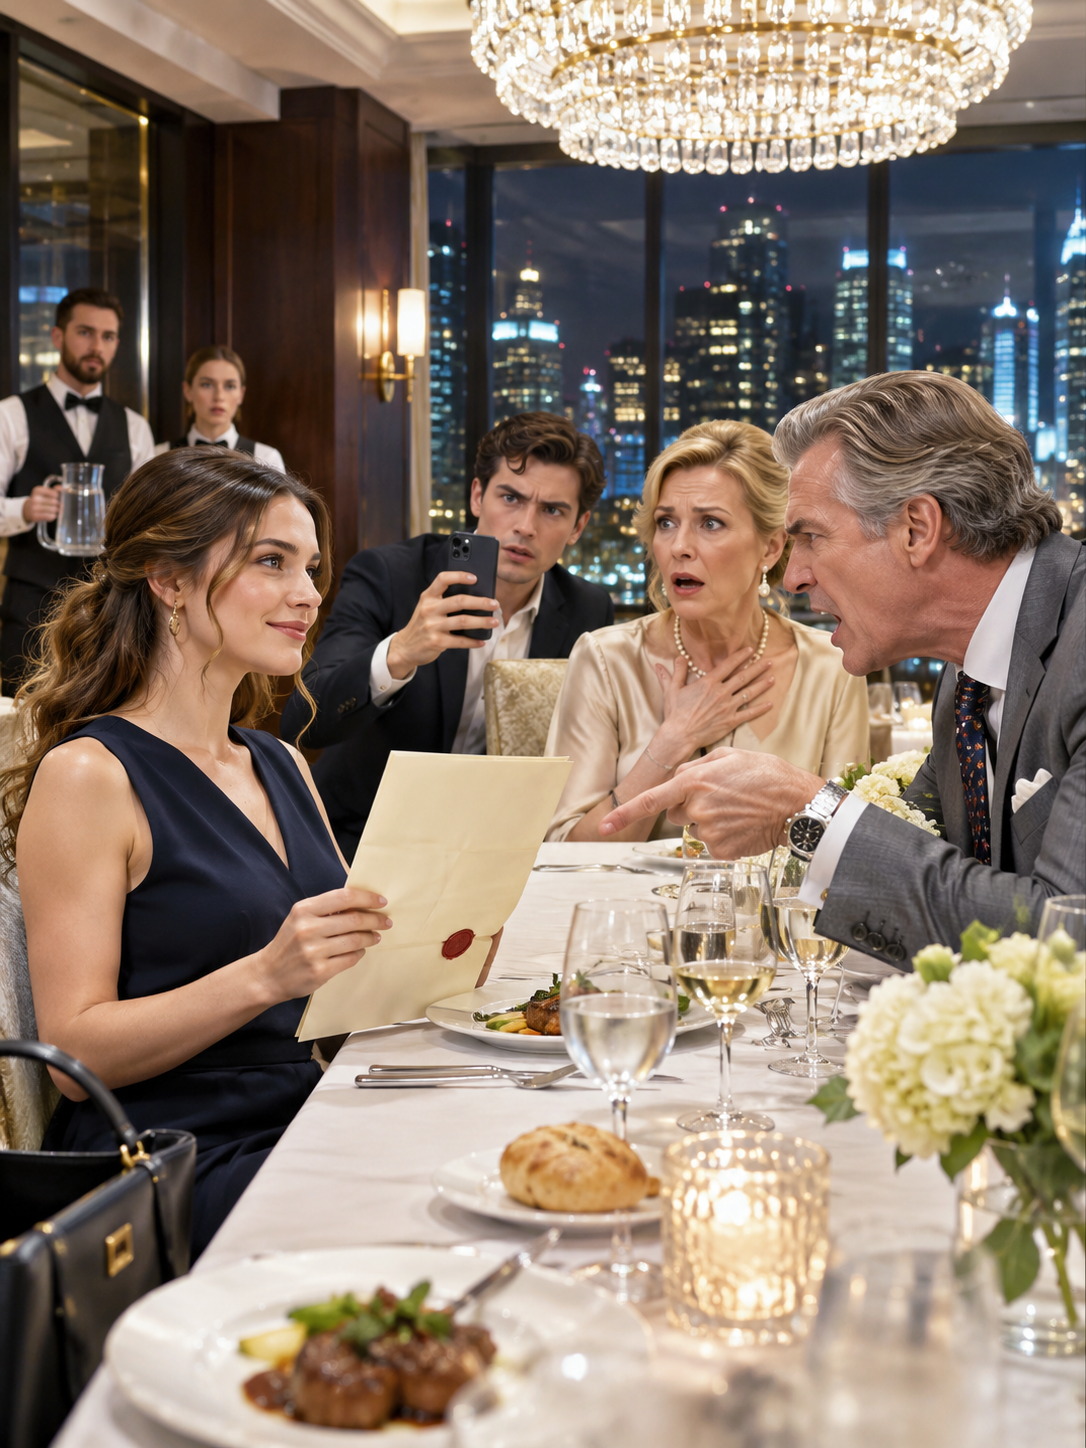
My father assigned half my salary to my brother between the roast chicken and the mashed potatoes. “Starting next month, Nina will send fifty percent of her take-home pay to Blake,” Walter Mercer announced, setting down his knife. “He has two boys to raise, and you’re single, Nina, so you can afford to help.” Around the table, everyone watched me as though I was expected to sign a check beside the gravy boat.
Blake leaned back with the satisfied smile he’d worn whenever our father paid his way out of trouble. “Finally,” he said, adjusting the expensive watch that he’d called a business necessity. His wife, Dana, stopped cutting her chicken, but Blake was already talking about a bigger house near Cincinnati’s best school district. Their sons were downstairs watching cartoons, blissfully unaware that their father’s plans depended on money I hadn’t offered.
I was thirty-three, a senior financial analyst earning $148,000 a year, and I had spent most of my adult life living under the accusation that I was lucky. I worked late, carried a mortgage, and paid my own way through graduate school after Dad financed Blake’s first business. Last winter, I covered an overdue equipment payment to protect Blake’s employees. Dad had thanked me by saying it was good to see me acting like family.
“What’s the amount supposed to cover?” I asked, setting my water glass beside the folded napkin. Blake mentioned his mortgage, daycare, and the rising price of lumber, but Dana looked sharply at him when he said daycare. She’d told me the previous week that both boys were enrolled in public school. Dad waved away my question and said, “The details aren’t yours to debate.”
The house smelled of rosemary and fireplace smoke, and a clock chimed eight from the hallway. Dad waited for me to object, already gathering the familiar speech about how lonely I’d become without a husband or children. Instead, I folded my napkin into a narrow square. “I understand,” I said, and his face briefly lost its certainty.
“That’s it?” he asked, leaning forward. I nodded, not agreeing to a transfer, merely acknowledging what I had heard. Blake grinned and told Dana that I was finally seeing sense. The distinction mattered to me, even if nobody at that table cared to notice it.
My phone vibrated against my knee with a message from Mara Ellis, the attorney I’d hired six weeks earlier. “Friday’s documents were acknowledged,” it read. “Do not discuss your accounts without counsel present.” I slid the phone into my purse and watched Dad pour Blake another glass of wine. The quiet relief I felt scared me more than the anger had.
On the drive home, I passed the office park where I regularly worked until midnight and remembered the day Dad had visited my hospital room four years earlier. I’d signed a limited financial power of attorney during an emergency surgery, trusting him to protect two accounts while I recovered. I had never formally asked for the paperwork back after returning to work. That oversight had haunted me since I learned what had been done with it.
At home I checked the copy of a bank notice resting inside my desk drawer, its corner softened from being opened too many times. It referred to an obligation connected to Blake’s framing company, even though I had never joined his business. I’d spent weeks tracing what the notice meant and gathering records before saying anything to my family. Now Dad and Blake were planning to visit the bank Monday, convinced they could turn my silence into permission.
Before bed, Mara called to confirm she would join me at the branch at nine. “They still think the old authorization works,” she said, and I heard pages turning in the background. I glanced at a signature reproduced at the bottom of the notice, one that looked almost like mine. By Monday, I intended to learn who had put it there.
Part 2
The first warning arrived six weeks before dinner in an envelope I nearly threw away. It was a routine-looking statement from a reserve account I’d built for emergencies, the kind of account I checked only at tax time. A transfer of $42,000 had left it under a description labeled “Mercer business support.” I stared at those words at my kitchen counter until the kettle boiled dry.
The branch customer service desk couldn’t disclose another customer’s records, so I requested the transaction documents involving my own reserve. I also checked the authorization Dad had used and learned it remained listed on one account even though I’d recovered long ago. “You can revoke it and notify the institutions,” the banker explained, “but the earlier transfer will require a separate review.” I went home with a stack of forms and a feeling that I’d left my front door unlocked for years.
Mara met me at her office above a bakery that smelled of cinnamon rolls. She was practical, with a pencil tucked behind one ear and no patience for family members who confused trust with ownership. We reviewed the power of attorney and immediately drafted a revocation, notice to the institutions, and a request for the complete payment trail. “Don’t accuse anyone of a crime before we know which documents exist,” she warned.
That night Dad called to ask why a bank representative had contacted him about updated permissions. I told him I’d resumed exclusive control of my accounts now that the medical emergency was long behind me. He laughed, then asked whether Blake had pressured me into doing something foolish. When I said no, Dad grew quiet and told me, “Some documents aren’t meant to be questioned.”
A second envelope arrived three days later from a commercial lender, addressed to me as an individual guarantor. I’d guaranteed a friend’s apartment lease once, years earlier, but never a business loan. The letter referred to an upcoming review involving Mercer Precision Framing and asked me to confirm current contact information. When I phoned the number printed on it, the employee directed me to the lender’s legal department.
I brought the letter to Mara rather than calling Dad. She requested records identifying me as a guarantor and instructed me to preserve every original envelope, statement, and message. Over the next week, the bank provided copies of documents it claimed supported my obligation. One contained a signature line bearing my full name, followed by an unfamiliar notarial acknowledgment.
The signature curved the way mine did on holiday cards, then ended with a long flourish I’d stopped using in college. I held the page beside my driver’s license and felt a sickening embarrassment, as if I were somehow responsible for someone copying me badly. Mara said similarity wasn’t proof of consent and arranged an independent examination. For the first time, the problem had a shape beyond the missing transfer.
I searched my calendar for the date on the paperwork and found a presentation I’d delivered in Pittsburgh that morning. My hotel invoice, conference badge, and workplace travel logs all placed me hundreds of miles from the local office named on the acknowledgment. That didn’t settle every question about how the paperwork was processed, but it gave Mara a solid discrepancy to investigate. She asked the lender to preserve its submission records.
By Friday, the lender had received formal notice disputing my supposed guarantee, and my personal banks had acknowledged the revoked authority. The investigation was far from complete, and the disputed reserve transfer had not magically returned to my account. But my salary account was secure, and no one else could authorize future payments from it. I tucked the acknowledgments into a leather folder before heading to Saturday’s family dinner.
Now, sitting at my desk the night after Dad’s announcement, I reread the guaranty that had appeared in the lender’s file. The principal obligation was $310,000, enough to devastate my savings if anyone successfully enforced it against me. Beneath the amount sat a signature I had never made. The question was no longer whether my family expected me to support Blake; it was how far they’d already gone without asking.
Part 3
On Sunday morning, I was halfway through a grocery list when Dana called from a number I didn’t recognize. Blake had gone to inspect a house in Oakridge, and she sounded embarrassed to be speaking to me privately. “Did you actually offer to pay part of our new mortgage?” she asked. I set down my pen and told her I hadn’t offered them anything.
Dana exhaled so hard I heard the wind hit her phone. Blake had told her my contributions were part of an investment arrangement Dad worked out months earlier, she said. He’d even shown her a spreadsheet with a projected monthly transfer based on my annual salary. When I asked who prepared the spreadsheet, she said Dad’s office assistant had emailed it to Blake last Tuesday.
“That’s before dinner,” I said. Dana went quiet, and I could hear one of the boys asking for cereal in the background. She insisted she wouldn’t accept money taken from me without permission, but she’d signed a preliminary purchase agreement believing Blake had legitimate financing. By the time she ended the call, I had a new question: why had my father treated Saturday’s announcement as a formality?
Mara and I met Sunday afternoon at her office, where rain tapped against the tall windows. Mara showed me the lender’s response to our preservation request, including the recorded date of the disputed guaranty and the names of people authorized to submit company paperwork. Dad had acted as Blake’s adviser during the loan application, and he was copied on several communications about the missing guarantor confirmation. One message from the lender explicitly requested direct confirmation from me, yet there was no record I’d replied.
“So how did they proceed?” I asked. Mara said the bank was investigating whether its own verification process had failed and whether anyone had misrepresented my consent. She wouldn’t promise that my name would disappear from the loan overnight, only that the documents gave us strong grounds to challenge liability. What frightened me was Dad’s presence on every exchange where someone should have stopped and called me.
Mara also showed me the receipt for Friday’s notices. My former power of attorney had been revoked in writing, and my banks had logged that revocation before Dad’s dinner speech. Any new instruction he gave on my behalf would be rejected, but the earlier $42,000 transfer still required investigation and possible legal recovery. She had scheduled Monday’s meeting after the bank invited both parties to address the disputed authorization.
Back home, I found a message from Blake: “Don’t make tomorrow difficult. Dad says you already agreed.” I answered with one sentence: “I authorized no payment and signed no business guaranty.” His reply arrived almost immediately. “You always have to turn everything into a legal issue.” I saved the exchange without responding further.
That evening Dana called again, softer this time, and admitted she had been trying to convince Blake to postpone the house purchase. She said the children didn’t need a bigger place, but Blake was afraid looking unsuccessful would hurt his business. When I asked if he’d told her about the $310,000 loan, she whispered, “He said that was already taken care of by your father.” Her words left me staring at the dark kitchen window.
At 8:45 Monday morning, Mara met me outside First County Bank. She carried a slim folder and asked whether I was prepared to hear unpleasant things without arguing with my father in the lobby. I nodded, because I knew anger might give him an excuse to dismiss everything as another family quarrel. Through the glass doors, I could already see Blake and Dad walking toward the private offices.
Dad wore the navy blazer he’d bought for my college graduation and carried a handwritten note about the salary payments he expected me to make. Blake kept checking his phone, probably thinking about the house appraisal scheduled for later that morning. When the branch manager, Mrs. Evelyn Calder, opened her office door, she looked past both men toward me and Mara. She said, “I’m glad you’re all here; we need to establish who actually has authority over Nina’s money.”
Part 4
Dad took the chair nearest Mrs. Calder’s desk, as though twenty years of banking at the branch entitled him to run the meeting. “Let’s clear up the misunderstanding,” he said, sliding forward his handwritten plan. “My daughter agreed Saturday to direct half her pay toward Blake’s business, and we need an automatic arrangement before his property appointment.” Mrs. Calder left the paper untouched and asked whether I had authorized any such debit.
“No,” I said. Dad turned toward me so sharply his chair creaked. “Nina, you said you understood,” he protested, and I answered, “I understood what you wanted; I never agreed to give you my earnings.” Blake muttered that I was embarrassing Dad, but Mrs. Calder raised a hand before the argument could spread.
She opened a restricted file and looked at the two men. “Didn’t Nina tell you she revoked the old power of attorney and disputed the guaranty?” she asked. Dad’s mouth opened, then closed, and Blake’s fingers stopped tapping his watch. For a moment the only sound was the printer humming behind Mrs. Calder’s desk.
Mrs. Calder explained that the revocation was effective for future instructions once received and that no one could set up a payroll transfer from my accounts without my valid authorization. The bank had also restricted changes related to the disputed guaranty while its investigation continued. My attorney clarified that the $42,000 withdrawal was separately contested and that its recovery was not automatic. Dad called the whole process an overreaction to a family favor.
“A family favor?” I repeated, placing a copy of the $310,000 guaranty beside his note. “Someone put my name on a commercial obligation I never agreed to assume.” Blake looked away, but Dad insisted the signature was genuine and that I’d forgotten a conversation during my recovery. I reminded him that the document was dated years after my surgery, on a day when I was presenting at a conference in Pittsburgh.
Then I asked how Blake intended to cover his company’s debt without my salary. He said the property purchase would help him win wealthier clients and claimed the business loan was mostly tied to equipment. I mentioned his overdue subcontractor bills, which Dana had quietly confirmed after hearing about them from an employee’s spouse. He stared at me as though asking questions were a greater betrayal than hiding liabilities.
Dad stood and rested his palms on the polished desk. “Your brother has a family, Nina, and all you have is your career,” he said. “If you leave this room without helping, don’t expect either of us to call you family again.” My throat tightened, not because I believed him, but because he’d found the cruelest way to describe the life I’d built. I told him, “You can’t take away something you never treated me as having.”
Mara directed all future discussions to counsel, and Mrs. Calder reminded Blake that the company’s loan would continue under its lawful terms while the review proceeded. No one seized a truck or emptied an account that morning; the real consequences would require notices, findings, and decisions the bank hadn’t yet made. Dad seemed almost offended that he couldn’t settle the question by ordering the manager to obey him. We left while he demanded to speak to her supervisor.
At six, Dana appeared at my door carrying a sealed envelope and looking as if she hadn’t slept. She apologized for arriving without warning and said she’d found documents while asking Blake why the bank had delayed their purchase. “I believed he was protecting our boys,” she said, holding the envelope by its corners. “But this has nothing to do with protecting them.”
Inside was a copy of a payment instruction connecting my missing reserve money to the deposit on a vacation property, with Walter Mercer’s name listed as a prospective co-owner. My father hadn’t merely wanted to rescue Blake’s business; he’d planned to benefit from the money taken from me. I stood in my doorway wondering how many years I’d mistaken his favoritism for love.
Part 5
Dana and I spread the envelope’s contents across my kitchen table while the dishwasher clicked through its final cycle. The vacation-property deposit was listed under a company Dad had quietly formed with Blake, not Mercer Precision Framing. The transaction reference matched the date and amount missing from my reserve, though the copies alone couldn’t establish the complete path of the money. Dana said she’d found the pages while trying to understand how her husband could afford another property when their mortgage was already overdue.
Dad called that Tuesday after hearing the documents had been submitted. He told me the lake property was supposed to become a family retreat and that he would have invited me when it was finished. “You used my reserve without telling me,” I said, watching rainwater slide down the office window. He didn’t deny benefiting from the arrangement; instead, he offered to put my name on a future guest list.
I told him there would be no private deal and that Mara would handle recovery of the money. He asked whether I was really prepared to throw away our relationship over a financial misunderstanding. “You decided I mattered less than Blake’s plans long before I hired a lawyer,” I said. When he tried to bring up Mom, I ended the call rather than let him borrow her memory to explain his choices.
The next three months were not a satisfying parade of instant consequences. The lender reviewed its guaranty process, verified my travel records, and examined the challenged documents while Blake negotiated with his creditors. I continued making my mortgage payments and going to work, but every unexpected number on my phone made my chest tighten. Mara kept reminding me that a disputed debt was not automatically resolved simply because the evidence looked strong.
Eventually, the lender confirmed in writing that it would not seek payment from me under the disputed guaranty and corrected its records. That letter went into my home safe beside the revocation notices. The $310,000 business obligation remained Blake’s company’s problem, subject to the lender’s rights against the actual borrowers and collateral. For the first time since the first strange envelope, I slept without checking my account before dawn.
Dad agreed to a civil settlement after the financial records linked my reserve transfer to the property deposit. The purchase was abandoned, and proceeds recovered from the transaction helped fund repayment of my $42,000 plus agreed costs. The institutions handled their own review of the unauthorized documents, separate from my settlement. I didn’t receive a dramatic courtroom apology, and I no longer wanted one.
Blake sold his boat, gave up the new-house purchase, and reduced his business to jobs he could afford to complete. A financial adviser helped arrange payment plans so the crews wouldn’t be stranded by another grand promise. Dana moved household savings into an account she controlled and told him the boys’ needs came before appearances. She didn’t ask me to fund his next attempt at success, which was the first sign anyone had learned anything.
Dad mailed a handwritten letter on my thirty-fourth birthday, apologizing for how the dinner had sounded and asking whether we could begin again. He still described the money as a temporary family arrangement and never acknowledged that he’d tried to control my salary. I read it once, then placed it in the folder with the bank documents. Forgiveness was not an installment I owed him because he’d finally noticed the cost of his actions.
That summer I used my vacation days for a trip to the coast with two friends, something I’d postponed every year when Blake needed financial help. On the first morning, I drank coffee on a balcony while gulls called above the water, and my phone lay quiet beside the chair. I had no husband or children, just as Dad had emphasized at dinner, but I had work I valued, friends who loved me, and a life no one else was entitled to spend. When the restaurant server brought our check that evening, I paid for my own meal and smiled at how ordinary freedom could feel.
Legal Notice: This story is a work of fiction. Names, characters, businesses, events, and incidents are the product of the author’s imagination or are used fictitiously. Any resemblance to actual persons—living or dead—or to actual events is purely coincidental. Thank you! 💓