My Son Froze My Credit Card at the Optical Store—Then Claimed I Was Too Old to Live Alone, Until I Found Where My Money Had Gone
My son froze my credit card while I was standing at an optical counter, leaving me humiliated in front of strangers. When I called him, he said the declined payment proved I was too old to manage my own life. I was seventy-one, recently widowed, and had trusted him with my finances for three years. What he didn’t know was that I’d already discovered suspicious withdrawals from my savings. And the documents waiting on my kitchen table revealed why he desperately wanted me to sell my house.
Part 1
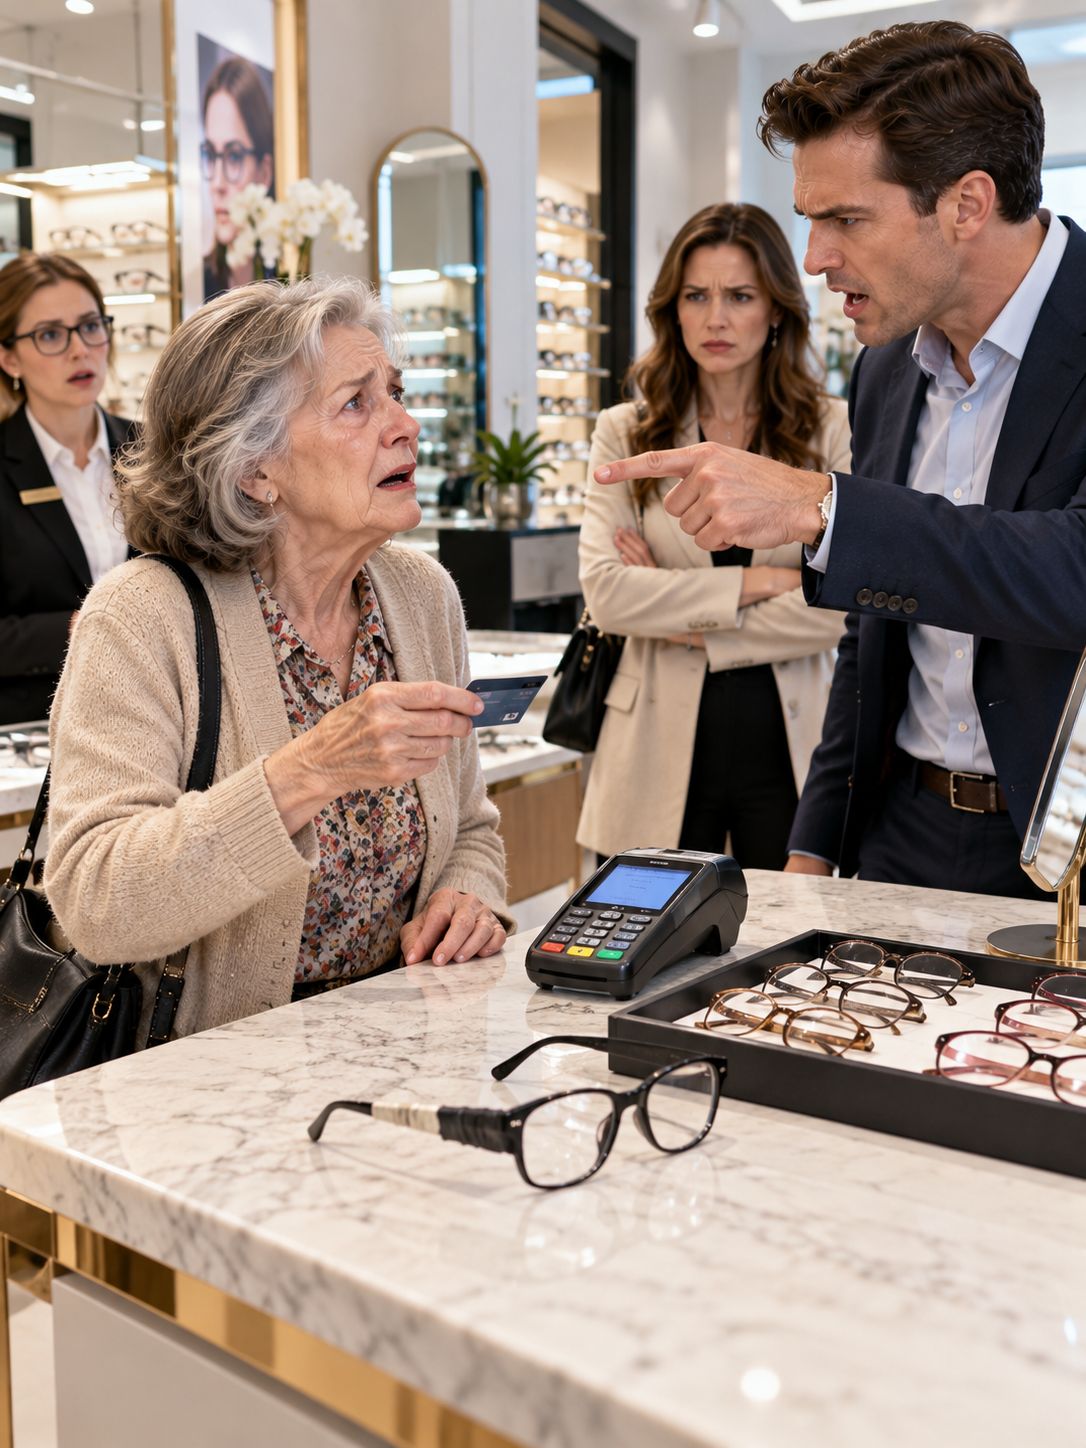
“Your card has been declined, sir,” the young woman behind the optical counter said, lowering her voice as another customer stepped closer. I stood beneath the harsh fluorescent lights of a Columbus shopping center, holding a receipt for the prescription glasses I’d just ordered. My old glasses lay beside the register, one crooked temple held together with electrical tape. When I called my son, Graham, he answered with a sentence that made my stomach tighten: “Dad, maybe this proves you shouldn’t be managing your money alone.”
I was seventy-one years old, but I wasn’t confused about what a pair of glasses should cost. The new frames were two hundred and eighty dollars, and I had considerably more than that in my accounts. Graham explained that he’d temporarily suspended my card because we needed to discuss my spending habits. Behind me, a woman quietly moved to another register, pretending she couldn’t hear our conversation.
“These are prescription glasses, Graham,” I said, stepping away from the counter. He replied that responsible financial planning required difficult decisions, especially at my age. Then he added, “We need to settle the house situation before you make any more unnecessary purchases.” I stared at the traffic passing beyond the store windows, understanding that the conversation wasn’t really about glasses.
My name is Walter Hayes, and I spent forty-three years working as a precision machinist outside Columbus, Ohio. I could measure a steel shaft within a thousandth of an inch, identify a defective bearing by its vibration, and repair most household equipment without calling a professional. Yet three years after my wife June died, I had somehow become a man whose own son believed he needed permission to buy glasses. The transformation hadn’t happened overnight.
June and I had been married for thirty-eight years when she died after a brief illness. She had managed our household bills while I handled repairs, yard work, and most financial decisions concerning our retirement savings. We had paid off our three-bedroom house twelve years earlier and accumulated enough money to live comfortably without extravagance. After she was gone, I discovered how many ordinary arrangements depended on knowledge she’d never needed to explain.
I knew where the furnace filter belonged but couldn’t immediately locate our homeowners insurance policy. I understood pension calculations but had trouble navigating the online account June used for automatic payments. My son stepped in without hesitation, bringing his laptop over on Sunday afternoons and organizing our accounts. His wife, Allison, occasionally delivered casseroles and reminded me that accepting help didn’t mean surrendering my independence.
At least, that was what I believed then. Graham owned a small residential remodeling company, and I had always admired his willingness to build something himself. He installed banking applications on my phone, arranged electronic statements, and recommended simplifying my finances. Eventually, an attorney prepared a limited financial power of attorney allowing him to handle certain routine transactions when I needed assistance.
For nearly two years, the arrangement seemed harmless. My bills were paid, the lawn was maintained, and Graham visited regularly enough that the house didn’t feel entirely abandoned. He sometimes complained that I kept too many old tools, especially a brass feeler gauge sitting on the kitchen windowsill. June had always returned that gauge to its place after cleaning, and I couldn’t bear to move it.
The first serious disagreement began when I broke my glasses while repairing a leaking valve beneath the laundry sink. Graham came over that Saturday carrying a folder instead of his usual toolbox. He spread a household expense summary across the kitchen table and announced that my home was consuming my retirement savings. According to his calculations, I was spending almost eight hundred dollars more each month than I received.
I examined the figures through my damaged glasses and asked about a line labeled “property maintenance reserve.” Graham explained that money was being set aside for future repairs, then quickly shifted to heating costs and insurance premiums. He suggested selling the house while the market remained favorable. I told him I’d consider downsizing someday, but I wasn’t ready to leave the home June and I had shared.
He produced a real-estate valuation estimating the property’s worth at approximately two hundred and eighty thousand dollars. Allison had apparently measured their spare bedroom and purchased curtains because they expected me to move in with them. Graham described how convenient everything would be, mentioning Sunday dinners and someone nearby in case I needed assistance. I listened, increasingly uncomfortable that so many decisions had been made without asking me.
“Let me see the actual bank statements,” I finally said. Graham promised to print them because the online account was supposedly too complicated to navigate. After he left, I tried signing in myself and discovered my usual password no longer worked. The recovery screen displayed the last four digits of Graham’s phone number instead of mine.
I wanted to believe there was an innocent explanation, perhaps something he’d changed while helping with automatic payments. Before I could call him, my phone rang with an unfamiliar number. The caller introduced herself as Rebecca Sloan, the woman who had previously handled bookkeeping for Graham’s remodeling company. She asked whether I could meet her privately the following morning.
I asked whether something had happened to Graham’s business, but Rebecca refused to discuss details over the telephone. “Mr. Hayes, please don’t sign anything concerning your house until we talk,” she said. When I asked why, her voice became unusually firm. “Because your son asked me to prepare financial figures that I couldn’t honestly put my name on.”
Part 2
Rebecca chose a diner near Henderson Road, where the windows were fogged from the heat of the kitchen. She was already sitting in a corner booth when I arrived, stirring a cup of coffee she hadn’t touched. Before I sat down, she asked whether Graham knew we were meeting. When I shook my head, she seemed relieved.
“I handled his business accounts for almost five years,” she began. “Last month, he asked me to prepare a summary showing that maintaining your house was financially impossible.” I told her he’d already shown me something resembling that description. Rebecca opened a small notebook and explained that she’d refused to prepare misleading figures. Graham terminated their working relationship three days later.
I asked whether she believed my son was stealing from me. Rebecca looked uncomfortable and said she couldn’t disclose his confidential business records. However, she knew enough about the proposed calculations to recommend examining my own statements carefully. “Start with the maintenance expenses,” she advised. “And don’t ask Graham for explanations until you have the original records.”
That afternoon, I visited my bank carrying my identification, account information, and a photograph of June tucked inside my wallet. The branch manager helped me obtain complete statements for the previous two years. I spread the pages across my dining table, marking unfamiliar withdrawals with a yellow highlighter. By midnight, I had discovered six transfers of nine hundred and fifty dollars each to a company called Hayes Residential Services.
That company belonged to Graham. The transfers were labeled “property maintenance reserve,” but nothing in my records showed that he’d established a separate reserve for my house. Additional payments covered furnace servicing, basement drainage, and structural repairs. Some amounts seemed reasonable until I started checking whether the work had actually occurred.
The first invoice concerned a furnace maintenance package supposedly completed in October. I searched the metal filing cabinet June had organized and found a receipt from an independent heating company dated eleven months earlier. When I called the company, its receptionist confirmed that no technician had visited since that appointment. Graham’s invoice claimed I’d paid for another service in the meantime.
The basement drainage invoice was even stranger. It listed a newly installed sump pump costing forty-two hundred dollars, including labor and materials. I walked downstairs carrying a flashlight and inspected every corner of the unfinished basement. There was no sump pump, no new drainage piping, and no evidence of installation work.
I sat on the bottom step, listening to the furnace rumble through its heating cycle. Graham had been in that basement dozens of times, sometimes helping me carry storage boxes or inspect plumbing. I remembered thanking him for taking care of things while I visited June’s sister in Dayton. Now I wondered whether the kindness I’d appreciated had provided convenient opportunities to move money unnoticed.
Over the following two days, I compared every invoice against photographs, receipts, and statements. One document described replacement of the porch’s structural supports, although the original wooden posts still carried pencil marks June and I had made while planning flower boxes. Another charged for drainage repairs that had never been performed. Including repeated transfers and unsupported charges, the questionable payments totaled twenty-four thousand six hundred dollars.
I almost called Graham immediately. Part of me wanted him to explain everything as a bookkeeping error or temporary loan that he’d intended to repay. His remodeling business had struggled with delayed payments before, and I’d occasionally helped him purchase equipment. But those loans had always involved a conversation, an agreed amount, and a clear understanding of when he would repay me.
Rebecca helped me organize the records without revealing anything belonging to Graham’s clients. She examined the dates and pointed out several expenses appearing twice in the summary he’d presented. “Your son hasn’t necessarily spent every dollar himself,” she cautioned. “But the numbers he’s using to convince you to sell don’t reflect what your house actually costs.”
That distinction mattered to me because I still wanted to be fair. I knew Graham carried responsibilities I didn’t fully understand, including payroll, equipment payments, and maintaining a household with Allison. I wasn’t interested in ruining his business over an honest mistake. Nevertheless, he had represented payments to his company as legitimate household expenses without telling me where the money went.
While gathering documents for an attorney, I found a second page attached to Graham’s real-estate valuation. It outlined how the proceeds from selling my home could supposedly support my retirement while allowing me to live with his family. Several expenses were listed as investments rather than living costs. At the bottom, an unexplained figure caught my attention.
The document proposed a family loan of one hundred and eighty thousand dollars, repayable when Hayes Residential Services achieved unspecified revenue targets. I had never requested such an arrangement, and Graham had never discussed borrowing anything close to that amount. Attached was an email from Allison saying, “Once Walter agrees to move, we can finalize the funding plan.”
Suddenly, their carefully decorated spare bedroom looked very different. My son’s insistence that I couldn’t afford to remain independent seemed connected to his expectation of receiving most of my home-sale proceeds. I placed the papers beside the questionable invoices, trying to understand how long they’d been planning this. Then I noticed the proposal was dated nearly four months before Graham first told me my retirement finances were in trouble.
Part 3
The attorney Rebecca recommended was named Patricia Wells, a woman in her early fifties whose office overlooked a busy street near downtown Columbus. She listened while I described June’s death, Graham’s assistance, the suspicious invoices, and the proposed loan. When I finished, she examined the limited power of attorney before asking whether I’d ever authorized gifts or loans to my son’s business. I told her I hadn’t.
Patricia explained that a financial power of attorney didn’t give Graham permission to treat my savings as his company’s property. However, proving unauthorized transactions would require documentation and careful examination of the arrangements we’d actually made. She recommended revoking his authority, securing my accounts, and requesting a formal accounting. I asked whether I could do those things without confronting him first.
“You’re the account owner, Mr. Hayes,” she answered. “You don’t need permission to protect your own money.” We completed the revocation documents and notified the bank through its required procedures. I changed passwords, replaced Graham’s recovery number with mine, and arranged for legitimate automatic payments to continue. For the first time in three years, I could see my finances without asking my son.
Patricia also helped me understand something I’d overlooked about my credit card. The account Graham had arranged for my routine purchases was actually his account, and I was merely an authorized user. He could restrict my use of that card, but doing so wouldn’t affect ownership of my savings or pension. She recommended obtaining payment cards connected directly to accounts in my name.
The bank arranged a replacement debit card, but it wouldn’t arrive immediately. Meanwhile, I continued investigating my household expenses and contacted the companies listed on Graham’s invoices. Several confirmed they had no records of the work he claimed to have commissioned. Patricia preserved those responses and prepared a formal request for repayment and supporting documentation.
Graham received notice that his authority had been revoked two days later. He called within an hour, demanding to know why I’d allowed an attorney to interfere with our family arrangements. I explained that I was reviewing my finances and wanted to manage them independently. He accused Rebecca of filling my head with suspicions, then insisted we discuss selling the house before making any permanent decisions.
I refused to commit to a sale. Graham immediately changed his tone, saying he was only concerned about my long-term security. He reminded me that living alone could become dangerous and that Allison had already prepared a comfortable bedroom. I thanked him for the offer and said I’d make my own decision after reviewing the facts.
Three days later, I visited the optical store to collect my new glasses. I brought the credit card Graham had issued because my replacement debit card hadn’t arrived, and using it had become an automatic habit. When the payment was declined, the clerk tried twice before explaining that the issuer had rejected the transaction. I called Graham, already suspecting what he’d done.
He admitted freezing the card because I refused to cooperate with his financial recommendations. “If you’re going to act irresponsibly, I need to establish some boundaries,” he told me. I looked at the glasses I’d waited two weeks to receive and asked what purchasing them had to do with selling my house. He answered that the larger issue was my declining judgment.
I ended the call before my anger became something I couldn’t control. The clerk offered to hold the glasses until the following day, and I thanked her for her patience. Driving home with my repaired old frames, I felt humiliated but also unexpectedly clearheaded. Graham hadn’t frozen the money I owned; he’d frozen a payment method he controlled, hoping I’d confuse the two.
That evening, I received a written message from him confirming the restriction. He said the card would remain unavailable until I agreed to meet a real-estate agent and establish a plan for selling my home. I forwarded the message to Patricia, who called immediately. “Keep that email,” she said. “It connects his financial pressure directly to the proposed property transaction.”
The following morning, I returned to the optical store and paid for my glasses with a personal check. The new lenses made the lettering on the receipt perfectly sharp, and I found myself smiling for the first time in days. At home, I prepared a folder containing the invoices, bank transfers, power-of-attorney revocation, and proposed loan. Patricia agreed to accompany me when I confronted Graham.
He invited me to Sunday lunch before I could suggest a meeting. Allison was making roast chicken, and he said a real-estate professional would be available to discuss my future. I accepted but mentioned that I would be bringing someone of my own. Graham sounded pleased, apparently assuming I’d finally decided to cooperate.
On Saturday evening, Patricia forwarded a final summary of the disputed transactions and proposed repayment demand. She also confirmed that the real-estate agent had no authority to list or sell my house without proper authorization. I placed those papers inside my folder, then took my brass feeler gauge from the kitchen windowsill. The following day, my son would discover that his father wasn’t nearly as helpless as he’d been telling everyone.
Part 4
Sunday arrived with low gray clouds and a cold drizzle that soaked the driveway outside Graham’s house. He opened the door wearing a pressed blue shirt embroidered with his remodeling company’s logo. The smell of roast chicken drifted from the kitchen, and Allison greeted me with an anxious smile. Then Patricia stepped inside behind me, carrying her briefcase, and Graham’s expression immediately changed.
“Why did you bring a lawyer?” he demanded before we’d even removed our coats. I told him I wanted someone present who could answer questions about the financial arrangements he’d proposed. In the dining room, a real-estate agent named Caroline Pierce was arranging brochures beside a property valuation. She looked distinctly uncomfortable when Patricia introduced herself.
Allison suggested eating first, but I placed my document folder on the table. “Before anybody discusses selling my house, I want Graham to explain a few expenses,” I said. I opened the folder to the basement drainage invoice and laid a photograph beside it. “Show me where this forty-two-hundred-dollar sump pump was installed.”
Graham studied the photograph before saying the invoice represented an estimate rather than completed work. I produced his original email describing it as a paid repair, complete with an invoice number and service date. He claimed the work had been postponed because a contractor was unavailable. Patricia quietly pointed out that the money had already left my account and been deposited into his business.
“Do you understand what it costs to run a company?” Graham snapped, pushing back his chair. I acknowledged that contracting could be difficult, especially when customers delayed payments. Then I placed the furnace invoice and the independent service company’s written confirmation beside the first document. “I’m asking why you charged me for repairs that never happened,” I said.
Allison leaned forward and examined the photographs. “You told me his house needed all this work,” she said to Graham. He insisted the repairs were still necessary and that I was misinterpreting business paperwork. When I asked why my retirement budget counted those same expenses twice, he stopped looking at me. Caroline quietly closed her real-estate portfolio.
Patricia explained that we had documented twenty-four thousand six hundred dollars in transfers and charges requiring a proper accounting. She presented the notice revoking Graham’s financial authority and confirmed that the bank had already removed his access. Graham stared at the paperwork, apparently struggling to understand why his usual explanations weren’t working. Then he accused me of forgetting everything he’d done after June died.
That accusation hurt because some of it was true. Graham had helped me when I was grieving, and I had been grateful for his time. I remembered how often I’d criticized him as a teenager, correcting mistakes before acknowledging effort. “I wasn’t always the father you deserved,” I admitted, watching his face soften briefly.
“But that doesn’t give you permission to take my money,” I continued. Graham looked away while Patricia placed the proposed family loan beside the disputed invoices. Allison asked why the loan amount was so large, and he finally admitted his company had accumulated serious financial obligations. He’d been hoping my house-sale proceeds would provide enough capital to stabilize the business.
I asked why he’d simply refused to tell me the truth. Graham said he knew I’d question the arrangement and might refuse to help. “I was trying to protect my family,” he insisted, glancing toward Allison. I reminded him that I was also his family and that he’d been willing to frighten me into surrendering my home.
Then I showed everyone the message linking my frozen credit card to agreement about selling the house. Caroline read it, stood, and announced that she had no intention of participating in a transaction without the owner’s informed consent. She gathered her brochures and excused herself. Graham watched her leave, his shoulders sinking as though the last part of his plan had disappeared through the doorway.
Allison turned toward her husband and asked whether he’d truly restricted my card to force a decision. He didn’t deny it, instead claiming that I’d become stubborn and refused sensible advice. Patricia gave him a formal demand for records and repayment, explaining that further legal action could follow if we couldn’t resolve the disputed transactions. Graham accepted the envelope without opening it.
I stood, thanked Allison for the invitation, and told Graham that all future financial discussions would go through Patricia. He followed me to the front door, asking whether I intended to ruin his business over money he would eventually repay. I answered that he’d already damaged our relationship by deciding deception was easier than asking for help. As I reached my car, I heard him call after me, “Dad, if you make me pay that money back now, you have no idea what else is going to collapse.”
Part 5
Graham refused to repay the money at first, claiming the transfers represented compensation for years of helping me manage my household. Patricia asked him to provide an agreement showing that I’d authorized those payments as compensation. He couldn’t produce one. After several weeks of unanswered requests and increasingly hostile messages, we filed a civil claim seeking an accounting and recovery of the disputed funds.
The legal process moved more slowly than I’d expected. Graham’s attorney challenged several expenses, and both sides exchanged bank records, invoices, and correspondence. I attended meetings where strangers discussed my retirement savings in language that made the betrayal sound almost ordinary. Still, every document confirmed that protecting myself had been necessary, regardless of how uncomfortable the process became.
Eventually, after additional business records were requested, Graham agreed to a settlement requiring repayment. The agreement included an initial payment and monthly installments, with provisions addressing missed payments. I didn’t recover every dollar immediately, and attorney fees reduced what I would ultimately keep. But the money was no longer being treated as something my son could take without answering for it.
Graham downsized his company, sold several pieces of equipment, and eventually accepted a salaried position with another contractor. I heard these developments through Patricia because I had stopped answering his personal calls. Part of me felt sad that the business he’d worked so hard to establish had deteriorated. Another part remembered how easily he’d decided that my financial security was an acceptable sacrifice for preserving it.
Allison wrote me a letter several months after the settlement. She admitted knowing Graham wanted to use the proceeds from my house to support his business, but maintained that she’d believed the arrangement had my approval. She apologized for helping present the move as a decision already made. I accepted that she might not have known about the false invoices, but I had no desire to resume our Sunday lunches.
Rebecca helped me establish a straightforward system for managing my monthly expenses. We organized my pension deposits, insurance payments, utilities, and household maintenance into separate categories I could review without assistance. She recommended an independent accountant for periodic checks, and I gladly followed that advice. Learning to manage everything myself took effort, but I preferred asking questions to surrendering control.
The following spring, I hired a plumber to replace the leaking valve beneath my laundry sink. He completed the job in less than an hour and charged an amount that appeared on a proper invoice. I watched him test the connection twice before packing his tools. After he left, I stood in the basement remembering the imaginary drainage system Graham had charged me thousands to install.
I also started volunteering at a community repair workshop, where retirees helped younger residents fix household items and understand basic maintenance. One Saturday, a teenager named Owen brought me a wooden shelf he’d built for his grandmother. It wasn’t perfectly square, and I immediately noticed the uneven joint. Then I remembered Graham building a crooked shelf in our garage when he was seventeen.
Back then, I’d pointed out every mistake before thanking him for the effort. That afternoon, I looked at Owen’s shelf and said, “You did a good job making something useful.” He smiled, and we spent twenty minutes adjusting the brackets together. I wished I’d understood earlier how much kindness mattered when teaching someone to improve.
Graham sent a birthday card in June, almost a year after the dispute began. Inside, he wrote that he missed me and hoped we could eventually return to being a family. He mentioned neither the unauthorized transfers nor the pressure he’d placed on me to sell my home. I read his words twice, then placed the card in a drawer without answering.
I still loved the boy who used to sit beside me in the garage, asking questions about machines. But the man he’d become had deliberately used my grief, trust, and uncertainty to make me doubt my ability to live independently. Missing him didn’t mean I needed to restore our relationship. I could acknowledge the mistakes I’d made as a father without accepting responsibility for the choices he’d made as an adult.
My house remained mine, and I had no plans to sell it. I repaired the porch, planted tomatoes beside June’s old rosebushes, and invited a few friends over for coffee on Sunday mornings. Sometimes I visited her grave and told her about the changes I’d made. I imagined she’d be pleased that I finally knew where every household document belonged.
One evening, I sat beside the kitchen window watching sunlight settle across the backyard. My brass feeler gauge rested on the sill, exactly where June used to put it after cleaning. I picked it up and turned it between my fingers, remembering that even the smallest gap could become a serious problem when pressure was applied. I had spent my working life understanding that principle, yet it had taken losing my wife’s protection to recognize it inside my own family.
I put the gauge back and opened the household account I’d learned to manage myself. The bills were paid, my savings were secure, and nobody else controlled whether I could purchase something as ordinary as a pair of glasses. Graham had wanted me to believe that growing older meant surrendering my independence to someone who claimed to know better. Instead, his betrayal had taught me something I should have understood years earlier: needing help didn’t make me helpless, and loving my son would never again mean giving him permission to decide how I lived.
Legal Notice: This story is a work of fiction. Names, characters, businesses, events, and incidents are the product of the author’s imagination or are used fictitiously. Any resemblance to actual persons—living or dead—or to actual events is purely coincidental. Thank you! 💓